Executive Summary
HDFC's migration documentation makes four things clear.
The original Swiggy HDFC Bank Credit Card is being phased out.
Migration is happening in batches rather than on one universal date.
Customers who take no action are moved to Swiggy Ornge.
HDFC says the migrated Ornge card will be lifetime free.
Once migration is completed, the original card cannot be reinstated.
For most light Swiggy users, I would take the lifetime-free Ornge.
For someone regularly spending roughly ₹2,000 or more per month on eligible Swiggy transactions, BLCK starts becoming financially interesting if the full standard annual fee applies.
And for anyone who used the old card heavily for both Swiggy and online shopping, BLCK is much closer to the product being lost because it maintains separate accelerated cashback buckets.
Cards Compared

Swiggy HDFC Bank Credit Card
Urban foodies, grocery delivery shoppers, and daily e-commerce spenders who order regularly on Swiggy, Instamart, and popular online platforms.
Swiggy Ornge HDFC Bank Credit Card
Historical Reference Only
In This Guide
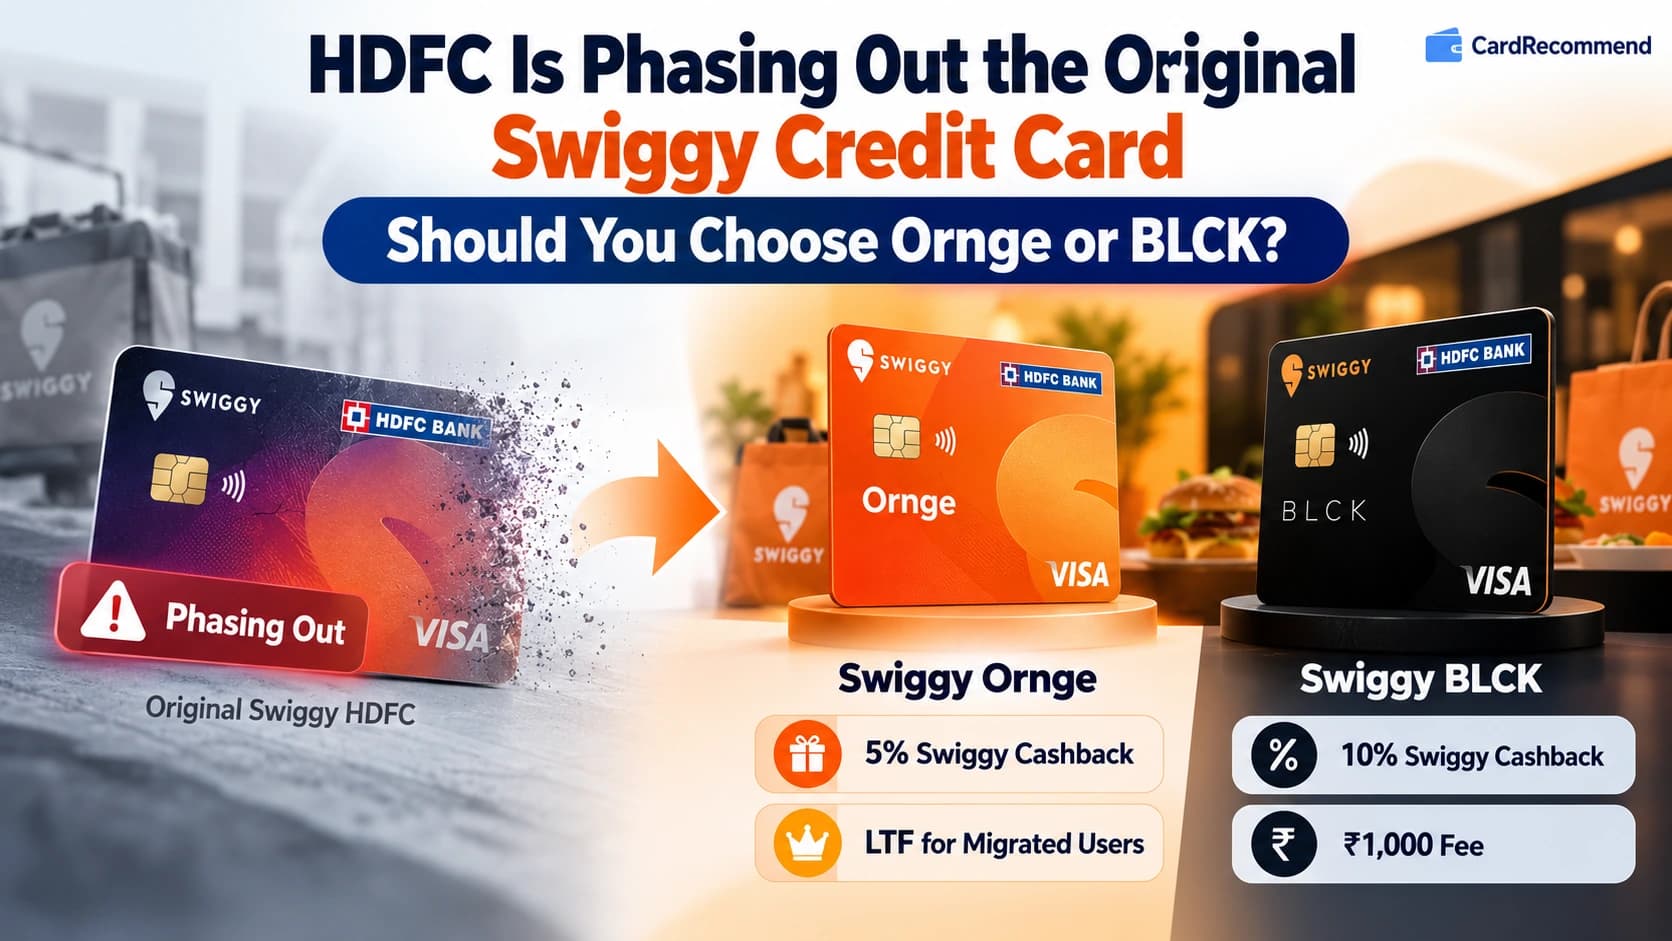
The original Swiggy HDFC Bank Credit Card is on its way out.
HDFC Bank has formally confirmed that the card is being phased out, with existing customers migrated in batches to the newer Swiggy card structure.
Customers are being given an opportunity to choose from the available replacement variants. If no preference reaches HDFC within the stated timeline, the bank says the card will be migrated to the Swiggy Ornge HDFC Bank Credit Card.
That default sounds harmless because HDFC also confirms that migrated Ornge will be lifetime free.
But there is a real devaluation hidden inside the switch.
The original Swiggy HDFC card gives 10% cashback on eligible Swiggy Food, Instamart and Dineout spending.
Swiggy Ornge cuts that to 5%.
Swiggy BLCK keeps the 10% rate but carries a standard annual fee of ₹1,000 plus applicable taxes, compared with ₹500 plus taxes on the original card.
So existing cardholders now have a real decision:
Take Ornge lifetime free and accept lower Swiggy cashback, or choose BLCK and pay more to retain the stronger cashback structure.
Terms verified: 20 October 2026
What Exactly Is HDFC Doing?
HDFC's official migration documentation says the original Swiggy HDFC Bank Credit Card is being phased out.
Eligible customers are being migrated in phases.
HDFC says customers will receive at least 30 days' notice before their scheduled migration, along with a tentative migration date.
This is why some existing cardholders have already received migration communications while others have not.
There is no single date on which every old Swiggy HDFC card suddenly stops working.
The rollout is customer-specific.
Swiggy's current credit-card proposition also now revolves around two HDFC variants:
Original Swiggy HDFC vs Ornge vs BLCK
| Feature | Original Swiggy HDFC | Swiggy Ornge | Swiggy BLCK |
|---|---|---|---|
| Swiggy Food / Instamart / Dineout | 10% | 5% | 10% |
| Swiggy cashback cap | ₹1,500/billing cycle | Part of accelerated 5% bucket | ₹1,500/billing cycle |
| Eligible online spends | 5% | 5% | 5% |
| Online cashback cap | ₹1,500/billing cycle | Shared accelerated cap | ₹1,500/billing cycle |
| Other eligible spends | 1% | 1% | 1% |
| 1% cashback cap | ₹500 | ₹1,000 | ₹1,000 |
| Standard annual fee | ₹500 + taxes | ₹500 + taxes | ₹1,000 + taxes |
| Migrated customer pricing | Until migration | Lifetime Free | Check personalised offer |
| Standard renewal waiver | ₹2 lakh | ₹1.5 lakh | ₹2 lakh |
| Welcome membership | Swiggy One | 12 months Swiggy One | 3 months Swiggy BLCK |
The Default Ornge Migration Is a Real Cashback Cut
The old Swiggy HDFC card's biggest attraction was its 10% cashback on eligible Swiggy transactions.
Suppose you spend ₹5,000 per month on eligible Swiggy Food, Instamart and Dineout transactions.
Original card:
₹5,000 × 10% = ₹500
Ornge:
₹5,000 × 5% = ₹250
Difference:
₹250 per month
Over one year:
₹250 × 12 = ₹3,000
So moving from the original card to Ornge is not simply a product rename.
For an active Swiggy user, it is a real cashback reduction.
But Migrated Ornge Is Lifetime Free
The standard public Swiggy Ornge card carries a ₹500 joining/renewal fee, with the renewal fee waived after ₹1.5 lakh of qualifying annual spending.
That is NOT the pricing HDFC specifies for customers migrated from the original card.
HDFC's migration documentation explicitly says the replacement Swiggy Ornge card will be:
Lifetime Free
That makes Ornge considerably more attractive for existing cardholders than its normal public pricing suggests.
There is no annual-spend requirement simply to keep a migrated Ornge card free.
The actual question is whether saving the annual fee compensates for losing half of the Swiggy cashback rate.
How Much Swiggy Spending Makes BLCK Worth It?
Swiggy BLCK's standard annual fee is:
₹1,000 + GST
At 18% GST:
₹1,180
Ornge gives 5% cashback on eligible Swiggy spending.
BLCK gives 10%.
Before either card reaches its cashback cap, BLCK therefore gives an extra:
5 percentage points
To recover a ₹1,180 annual cost:
₹1,180 ÷ 5% = ₹23,600 annual eligible Swiggy spend
Per month:
₹23,600 ÷ 12 = approximately ₹1,967
So the simplified break-even point is roughly:
₹2,000 per month of eligible Swiggy spending
At that level, BLCK's additional cashback can approximately recover its standard annual fee.
Real-World Break-Even Examples
Assuming the user pays the full ₹1,180 annual BLCK cost:
| Monthly eligible Swiggy spend | Ornge at 5% | BLCK at 10% | Extra BLCK cashback/year | Net advantage after ₹1,180 fee |
|---|---|---|---|---|
| ₹1,000 | ₹50 | ₹100 | ₹600 | -₹580 |
| ₹2,000 | ₹100 | ₹200 | ₹1,200 | ₹20 |
| ₹5,000 | ₹250 | ₹500 | ₹3,000 | ₹1,820 |
| ₹10,000 | ₹500 | ₹1,000 | ₹6,000 | ₹4,820 |
| ₹15,000 | ₹750 | ₹1,500 | ₹9,000 | ₹7,820 |
For someone spending ₹5,000–₹15,000 per month on eligible Swiggy transactions, BLCK becomes much easier to justify.
But there is an important cap effect.
Compare Swiggy Ornge vs Swiggy BLCK
Calculate net cashback yields at your monthly Swiggy spend, compare annual fee waiver conditions, and see whether BLCK's 10% rate covers its annual cost.
Spending More on Swiggy Does Not Always Make BLCK Better
BLCK's 10% Swiggy cashback is capped at ₹1,500 per billing cycle.
That means BLCK reaches the cap at:
₹15,000 × 10% = ₹1,500
Ornge earns 5%, so it reaches ₹1,500 at:
₹30,000 × 5% = ₹1,500
So if someone spends ₹30,000 a month only on eligible Swiggy transactions, both products could eventually generate the same ₹1,500 cashback ceiling.
That means very high Swiggy spending alone does not automatically make BLCK better.
BLCK's bigger advantage for heavy users comes from its separate online cashback bucket.
Separate Cashback Caps Are a Major BLCK Advantage
The original Swiggy HDFC card effectively gave users separate accelerated earning opportunities:
- up to ₹1,500 from Swiggy cashback
- up to ₹1,500 from eligible online cashback
BLCK preserves that structure.
Ornge does not provide the same separation.
Suppose in one billing cycle you spend:
₹15,000 on eligible Swiggy transactions
and:
₹30,000 on eligible online transactions
BLCK:
Swiggy:
₹15,000 × 10% = ₹1,500
Eligible online:
₹30,000 × 5% = ₹1,500
Total accelerated cashback:
₹3,000
For someone who used the original card heavily for both Swiggy and online shopping, this can be more important than the headline annual fee.
BLCK's Fee Can Also Be Waived
Under HDFC's current standard terms:
- joining fee can be waived after ₹75,000 of spending within the first 90 days
- renewal fee can be waived after ₹2 lakh of qualifying annual spending
If you naturally hit those thresholds, BLCK becomes substantially more compelling.
However, existing original-card holders should check the exact migration offer sent by HDFC.
Do not assume somebody else's BLCK migration offer on Reddit or social media will also apply to you.
The lifetime-free treatment is clearly confirmed for migrated Ornge.
BLCK migration pricing can depend on the personalised offer.
Ornge Is Not a Bad Card
It is easy to describe Ornge as a bad replacement because Swiggy cashback falls from 10% to 5%.
That would be too simplistic.
For an existing holder receiving it lifetime free, Ornge can still be a useful card.
It provides accelerated cashback on eligible Swiggy and selected online transactions, 1% on other eligible spending, and a 12-month Swiggy One welcome membership under the current proposition.
If you spend only ₹500–₹1,000 per month on Swiggy, paying ₹1,000 plus GST for BLCK purely to double that cashback is difficult to justify.
In that case, keeping Ornge lifetime free is perfectly reasonable.
BLCK Is Much Closer to the Original Swiggy HDFC Card
BLCK preserves the main thing that made the old card attractive:
10% cashback on eligible Swiggy Food, Instamart and Dineout transactions.
It also retains a separate 5% online cashback bucket and increases the 1% cashback ceiling compared with the old card.
The decision should not primarily be based on its golf benefit, membership branding or premium positioning.
The main reason to choose BLCK is simple:
You use Swiggy enough that 10% cashback is materially more valuable to you than Ornge's 5%.
What Happens If You Do Nothing?
If HDFC does not receive your preference within the specified migration period, the original Swiggy card will be migrated to:
Swiggy Ornge HDFC Bank Credit Card
HDFC says this migrated Ornge card will be:
Lifetime Free
Doing nothing therefore does NOT mean keeping your old card.
It means accepting Ornge by default.
Your Card Number Will Change
The replacement card receives a new card number.
This is not simply HDFC changing the product name in its systems.
Transactions performed on the original card before it is disabled will still appear appropriately in the migrated account/statement structure.
But the new card number creates an important practical problem.
Autopays and Standing Instructions Will Not Automatically Move
HDFC says existing:
- autopays
- e-mandates
- standing instructions
do NOT automatically transfer to the replacement card.
You must update them using the new card details.
Before using the replacement card, make a list of recurring payments currently attached to the old card.
Examples might include:
- OTT subscriptions
- insurance payments
- utilities
- cloud/software subscriptions
- memberships
- recurring merchant charges
Missing this step could cause payment failures after the old card is disabled.
Card Controls Must Also Be Configured Again
Existing transaction controls are not automatically carried across.
After receiving the new card, recheck:
- transaction limits
- online transaction permission
- contactless settings
- international usage
- ATM/cash controls where relevant
- merchant transaction settings
Do not assume your old security preferences remain active.
When Does the Old Card Stop Working?
HDFC says the original card is disabled at the earliest of:
- You begin transacting using the replacement card.
- 60 days pass from the migration date.
- The old card reaches its existing expiry date.
This gives customers a transition window.
I would use that window intelligently.
First update your recurring mandates and card controls.
Then begin using the replacement card.
You Must Activate the Replacement Card
The new card must be activated within the applicable RBI/HDFC activation period.
HDFC's migration documentation states that if the replacement card is not activated within 37 days from issuance, it may be closed in accordance with regulatory requirements.
So do not simply leave the new card unopened for months.
Your Renewal Date Resets
The new card begins a new membership cycle.
The annual membership renewal date changes to the migration date rather than continuing from the original Swiggy card's old renewal schedule.
For migrated lifetime-free Ornge holders this has little financial impact.
For a fee-bearing replacement, it matters.
You Cannot Switch Back to the Original Card
Once migration is completed, the old Swiggy HDFC Bank Credit Card cannot be restored.
HDFC says the previous card cannot be reinstated because the product is being phased out/discontinued.
So treat your replacement choice as a real migration decision.
What If You Have Not Received an Email Yet?
Do not panic.
HDFC says migration is taking place in phases.
Different customers can therefore receive communication at different times.
If another Swiggy HDFC cardholder already received an email and you have not, that does not necessarily mean anything is wrong.
Wait for your own official HDFC communication.
Also do not assume you will permanently retain the original card merely because your migration email has not arrived yet.
Should You Close the Card Instead?
Some users may decide that neither Ornge nor BLCK fits their wallet.
Closing the card can be rational if you genuinely no longer need it.
But do NOT close the old card simply because Reddit or social media claims doing so will guarantee approval for an HDFC core card.
HDFC does not guarantee that.
Decide based on whether the replacement product is useful to you.
Choose Swiggy Ornge If
Choose Ornge if:
- you want a lifetime-free replacement
- your Swiggy spending is relatively low
- you already have another strong online-shopping card
- you do not want to track annual fee waivers
- the Swiggy card is now only a secondary card in your wallet
For someone spending less than roughly ₹2,000 per month on eligible Swiggy transactions, paying BLCK's full standard fee purely for the extra cashback is difficult to justify.
Choose Swiggy BLCK If
Choose BLCK if:
- Swiggy is a major monthly spending category
- you want to retain 10% eligible Swiggy cashback
- you regularly spend ₹5,000–₹15,000 per month on Swiggy
- you also use the card heavily for eligible online purchases
- you can naturally meet its fee-waiver thresholds
- losing the original card's separate accelerated cashback buckets would materially reduce your rewards
Compare Swiggy Ornge vs Swiggy BLCK
Calculate net cashback yields at your monthly Swiggy spend, compare annual fee waiver conditions, and see whether BLCK's 10% rate covers its annual cost.
Check Which Swiggy Card Fits Your Spending
Enter your monthly Food, Instamart and Dineout spending in CardRecommend's calculator to evaluate real rupee cashback after fees and compare all options.
CardRecommend Verdict
The original Swiggy HDFC Credit Card is being replaced by a weaker free option and a stronger paid option.
For most low-to-moderate Swiggy users, I would take Swiggy Ornge lifetime free.
Yes, dropping from 10% to 5% cashback hurts.
But if you spend only ₹1,000 per month on eligible Swiggy transactions, BLCK generates roughly ₹600 more cashback per year — not enough to justify a ₹1,180 standard annual cost after GST.
At around ₹2,000 per month, BLCK begins to approximately break even under the simplified standard-fee calculation.
At ₹5,000–₹15,000 per month, BLCK becomes increasingly attractive.
But do not judge the products only on 10% versus 5%.
BLCK's bigger structural advantage is that its Swiggy and eligible online cashback limits remain separate.
For someone who used the original Swiggy HDFC card heavily across both categories, that makes BLCK much closer to the product being lost.
So my recommendation is:
Choose Ornge if you want zero annual cost and your Swiggy use is modest.
Choose BLCK if Swiggy is a major spending category or you also use the card heavily for eligible online purchases.
And whatever you choose, do not ignore the migration operationally.
Your card number changes.
Your mandates do not automatically transfer.
Your card controls need to be configured again.
Your renewal cycle resets.
And once the old card is migrated, HDFC says you cannot get it back.
HDFC has effectively split one unusually attractive product into two compromises:
Ornge keeps the free card.
BLCK keeps the stronger rewards.
You now have to decide which part mattered more.
Check Which Swiggy Card Fits Your Spending
Enter your monthly Food, Instamart and Dineout spending in CardRecommend's calculator to evaluate real rupee cashback after fees and compare all options.
Cards Discussed in This Article

Swiggy HDFC Bank Credit Card
Frequently Asked Questions
Is the original Swiggy HDFC Bank Credit Card being discontinued?
Yes.
HDFC Bank says the original Swiggy HDFC Bank Credit Card is being phased out, with migration happening in batches.
What happens if I do not choose Ornge or BLCK?
HDFC says customers who do not submit a preference within their stated migration window will be moved to Swiggy Ornge.
Is migrated Swiggy Ornge lifetime free?
Yes.
HDFC's migration FAQ specifically states that the Ornge card issued through migration will be Lifetime Free.
This is different from normal public Ornge pricing.
Does Swiggy Ornge give 10% cashback?
No.
Swiggy Ornge gives 5% cashback on eligible Swiggy Food, Instamart and Dineout transactions under its current structure.
Does Swiggy BLCK give 10% cashback?
Yes.
BLCK currently offers 10% cashback on eligible Swiggy Food, Instamart and Dineout spending, subject to its billing-cycle cashback cap.
What is the Swiggy BLCK annual fee?
The standard joining and renewal fee is ₹1,000 plus applicable taxes.
Existing cardholders should check the personalised HDFC migration communication for the exact offer available to them.
How much should I spend before BLCK becomes better than Ornge?
Under the simplified calculation where BLCK costs ₹1,180 including 18% GST and both cards remain below cashback caps, the additional 5% cashback covers the annual fee at approximately ₹1,967 of eligible Swiggy spending per month.
Will my existing autopays transfer?
No.
Because the replacement card receives a new number, HDFC says existing autopays, mandates and standing instructions do not automatically move.
Will my card number change?
Yes.
The replacement card has a new card number.
Can I return to the old Swiggy HDFC card later?
No.
HDFC says the old card cannot be reinstated after migration.

Founder & Editor, CardRecommend
Founder & Editor of CardRecommend. Dedicated to researching credit card reward structures, fee waivers, airport lounge policies, and calculating real user value across Indian financial products.