Prefer to compare all RuPay UPI cards?
Browse and filter all 24 verified RuPay credit cards by apps, zero fees, and UPI reward rates in our live directory.
Executive Summary
Paytm AU is a lifetime-free RuPay card offering up to 2% on Paytm UPI and 5% on Paytm Travel and Gold. Its headline 12 family lounge visits are valuable — but only after qualifying Paytm flight bookings.
Reviewed Card
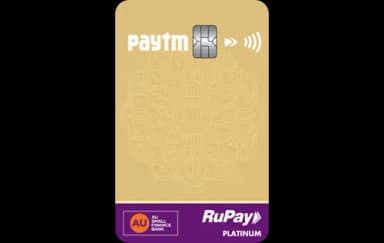
Paytm AU Credit Card
Paytm UPI spends, Paytm Travel flight bookings, and Paytm Gold
In This Guide
The Paytm AU Small Finance Bank Credit Card has one of the more unusual combinations in India's crowded RuPay credit-card market.
It is lifetime free, rewards eligible Paytm UPI payments, gives accelerated rewards on Paytm Travel and Paytm Gold, and advertises as many as 12 family airport-lounge visits per year.
That last number is also the easiest part of the card to misunderstand.
This is not a credit card where you receive 12 unconditional lounge visits merely because the card is in your wallet.
The lounge entitlement is connected to eligible round-trip flight bookings made through Paytm Travel.
Paytm's current guidance says a qualifying booking of ₹5,000 or more unlocks the family lounge benefit, while current launch material describes access for up to four family members together and up to 12 visits annually.
So the real proposition is much more specific:
Use Paytm heavily for UPI and travel, and this can be an unusually rewarding lifetime-free card.
If you do not want your rewards and travel benefits tied to the Paytm ecosystem, much of the headline value disappears.
Terms verified: 21 October 2026
First, This Is Not Really a Brand-New October Launch
Fresh coverage in October 2026 describes Paytm and AU Small Finance Bank as formally launching or promoting the co-branded card.
But the product itself has been visible for months.
Launch coverage and Paytm product material existed earlier in 2026, and cardholders were already discussing actual usage before this fresh October push.
So CardRecommend should NOT describe this as if the card suddenly became available for the first time today.
The better framing is:
the Paytm AU card is receiving a fresh formal launch/marketing push, and its current proposition is now clear enough to audit properly.
Financial terms must come from current AU and Paytm documentation rather than simply repeating launch headlines.
Paytm AU Credit Card Benefits at a Glance
| Feature | Current proposition |
|---|---|
| Joining fee | ₹0 |
| Annual fee | ₹0 |
| Network | RuPay |
| Paytm UPI rewards | Up to 2% |
| Paytm UPI above ₹2,000 | 1% |
| UPI through other apps | 0.25% |
| Paytm Travel | 5% |
| Paytm Gold | 5% |
| Paytm recharges/bill payments | 1% |
| Other eligible online/offline spends | 1% |
| Reward value via Paytm Gold | ₹1 per Reward Point |
| Other redemption value | ₹0.50 per Reward Point |
| Reward caps | Three separate 1,000 RP monthly buckets under current published structure |
| Family lounge access | Up to 12 domestic family lounge visits/year |
| Lounge trigger | Eligible ₹5,000+ round-trip Paytm flight booking |
| Fuel surcharge waiver | 1%, subject to applicable limits |
The card currently has:
₹0 joining fee
and:
₹0 annual fee
making it lifetime free under the current AU proposition.
The 2% UPI Reward Is Real — But Only in the Right Setup
Paytm UPI is the central reason this card exists.
The current published reward structure shows:
| Transaction | Reward rate |
|---|---|
| Eligible Paytm UPI up to ₹2,000 | 2% |
| Eligible Paytm UPI above ₹2,000 | 1% |
| UPI through other apps | 0.25% |
That makes the card especially useful for frequent smaller merchant UPI transactions.
Example:
Ten eligible ₹2,000 Paytm UPI transactions:
Total spend:
₹20,000
At 2%:
₹20,000 × 2% = 400 Reward Points
If redeemed for Paytm Gold:
400 RP = ₹400
That is a genuine 2% effective return.
But if you make one ₹20,000 Paytm UPI transaction, that transaction sits in the higher-value transaction band and earns at the lower rate.
The product is therefore more attractive for the kind of smaller everyday UPI payments people already make regularly.
Do Not Hardcode an Unverified ₹100 Minimum Yet
Several secondary descriptions and older community discussions state that the 2% UPI tier applies specifically to transactions between:
₹100 and ₹2,000
However, CardRecommend should not hardcode that ₹100 lower boundary unless the current issuer-specific Reward Point T&C directly confirms it.
The ₹2,000 upper breakpoint is verified.
The lower transaction boundary should remain an internal fact-check item until captured from current AU issuer documentation.
Do NOT invent it.
Using Another UPI App Cuts the Reward Sharply
This is a RuPay credit card, but the strongest UPI reward is tied specifically to Paytm.
Current Paytm guidance shows UPI transactions through other apps earning only:
0.25%
compared with up to:
2% through Paytm UPI
Example on ₹20,000 of eligible spend:
Paytm UPI at 2%
₹400 effective value
Other UPI app at 0.25%
₹50 effective value
So this is not merely a good RuPay UPI card.
It is specifically a:
Paytm-first UPI credit card
If Paytm is not the user's preferred UPI app, the headline 2% proposition becomes much less useful.
The Headline Reward Rates Assume Paytm Gold Redemption
This is one of the most important details.
AU's current proposition values:
1 Reward Point = ₹1 when redeemed for Paytm Gold
but:
1 Reward Point = ₹0.50 across other applicable redemption categories
That means the advertised percentages require context.
| Earning category | Value via Paytm Gold | Approx. value at ₹0.50/RP |
|---|---|---|
| Paytm UPI top tier | 2% | 1% |
| Paytm UPI above ₹2,000 | 1% | 0.5% |
| Other UPI apps | 0.25% | 0.125% |
| Paytm Travel / Gold | 5% | 2.5% |
| Eligible base spending | 1% | 0.5% |
Therefore:
DO NOT describe the card as giving direct 5% cashback.
The correct language is:
5% effective reward value when redeemed optimally for Paytm Gold
unless the CardRecommend UI separately explains the Reward Point conversion.
Reward Caps Matter
Paytm's current official guide publishes three monthly Reward Point limits:
- 1,000 Reward Points on UPI spends
- 1,000 Reward Points on Paytm / e-commerce spends
- 1,000 Reward Points on offline / POS spends
This creates a headline maximum of:
3,000 Reward Points per month
across the three published buckets.
If all 3,000 points are redeemed for Paytm Gold:
3,000 RP = ₹3,000
But the buckets must be stored separately.
Do NOT simply create a generic:
“3,000 RP monthly cap”
without preserving the underlying bucket structure.
At a 5% earn rate:
₹20,000 × 5% = 1,000 Reward Points
so around ₹20,000 of qualifying spending can consume a 1,000-point accelerated bucket where the transaction maps to that bucket.
<div className="not-prose my-8 p-5 sm:p-6 rounded-2xl border border-orange-500/30 bg-[#070D1B] flex flex-col sm:flex-row items-start sm:items-center justify-between gap-4"> <div> <span className="text-[10px] uppercase font-bold tracking-widest text-orange-400 block mb-1">CARD SPOTLIGHT</span> <h4 className="text-base sm:text-lg font-bold text-white">Auditing the Paytm AU Credit Card?</h4> <p className="text-xs sm:text-sm text-slate-300">View complete verified fees, monthly reward caps, and application eligibility.</p> </div> <div className="flex flex-wrap items-center gap-3 w-full sm:w-auto"> <a href="/credit-cards/paytm-au-credit-card" className="flex-1 sm:flex-none text-center px-4 py-2.5 rounded-xl bg-[#FF5B00] hover:bg-[#e05000] text-white font-bold text-xs transition">View Paytm AU Credit Card</a> <a href="/card-categories/upi-rupay" className="flex-1 sm:flex-none text-center px-4 py-2.5 rounded-xl bg-[#121B2D] hover:bg-slate-800 text-slate-200 border border-slate-700 font-bold text-xs transition">Compare UPI Credit Cards</a> </div> </div>
Paytm Travel and Paytm Gold Are the 5% Categories
Eligible spending on:
- Paytm Travel
- Paytm Gold
currently earns:
5 Reward Points per ₹100
At the optimal Paytm Gold redemption value:
5 RP = ₹5
meaning:
5% effective value
Example:
₹10,000 qualifying Paytm Travel booking:
500 Reward Points
Optimal Paytm Gold value:
₹500
That is strong for a lifetime-free card.
But do not generalise the Gold reward.
The card does NOT give 5% on jewellery or gold purchases everywhere.
The accelerated category is specifically:
Paytm Gold
The 12 Lounge Visits Are Not Unconditional
This is the single most important implementation rule.
DO NOT store or show:
“12 complimentary lounge visits/year”
without the booking condition.
The accurate proposition is:
Up to 12 booking-linked domestic family lounge visits per year
The current Paytm guidance links lounge access to an eligible:
₹5,000+ round-trip flight booking through Paytm using the Paytm AU card
Fresh launch material also describes the benefit as supporting:
up to four family members together
subject to applicable conditions.
So this is NOT equivalent to a conventional card that provides lounge access whenever the cardholder wants.
Why the Family Lounge Structure Is Interesting
Most low-cost credit cards give lounge access only to the primary cardholder.
Paytm AU is designed differently.
The lounge benefit is linked to a qualifying family trip.
For the right customer, this can be much more valuable.
A family of four travelling together may get more practical value from one qualifying family lounge activation than from a traditional card that gives four individual visits usable only by the primary cardholder.
But the benefit is also much narrower.
If the user:
- books directly with the airline
- books through another OTA
- does not meet the eligible round-trip booking condition
then the lounge benefit should not be assumed to apply. Check domestic airport lounges and requirements on our Airport Lounge Checker.
This Is Not Conventional Lounge Access
CardRecommend must treat this as a:
conditional travel benefit
not as a universal lounge entitlement.
Do NOT display it in the same way as:
“2 complimentary domestic lounge visits per quarter”
unless the UI clearly distinguishes the qualification mechanism.
Recommended backend wording:
lounge_type: conditional_family_domestic
annual_max: 12
trigger: eligible round-trip Paytm flight booking
minimum_booking_value: ₹5,000
family_access: supported under current offer
maximum_family_members: DO NOT hardcode exact interpretation unless issuer T&C confirms whether the primary cardholder is included in the “four family members” wording.
Do Not Automatically Value 12 Visits at ₹12,000
Avoid fake value calculations.
A lounge visit only has practical value when:
- the cardholder was already travelling
- the qualifying trip exists
- the airport has an eligible lounge
- the user would have otherwise paid or valued the visit
- the Paytm booking requirement is satisfied
Do NOT create an inflated annual-benefit number merely by assigning arbitrary rupee values to all 12 visits.
Paytm Travel Rewards Plus Lounge Access Can Be Strong
Example:
Eligible ₹20,000 round-trip Paytm flight booking.
At 5% reward value:
₹20,000 × 5% = 1,000 Reward Points
At optimal Paytm Gold value:
₹1,000
If the booking also satisfies the lounge-access conditions, the family can receive additional non-cash value.
That is a strong travel proposition for a card with:
₹0 joining fee
and:
₹0 annual fee
But reward caps still apply.
Do not extrapolate 5% infinitely.
General Spending Is Fine, Not Exceptional
Eligible normal online/offline spending currently earns:
1 Reward Point per ₹100
At Paytm Gold value:
1%
At ₹0.50 alternative point value:
0.5%
That is acceptable for a lifetime-free card.
It is not a reason to use Paytm AU for every purchase.
The strongest use cases are:
- Paytm UPI
- Paytm Travel
- Paytm Gold
Reward Exclusions Matter
Current Paytm guidance lists broad exclusions including categories such as:
- wallet reloads
- non-Paytm jewellery/gold
- international transactions
- EMI
- rent / real estate
- insurance
- education
- government transactions
- fuel
- utilities outside the applicable Paytm-specific structure
Do NOT invent exact MCC codes unless AU's current card-specific Reward Point T&C is available.
Store broad exclusions only where verified.
Fuel Gets a Surcharge Waiver, Not Rewards
Current AU documentation gives the card a:
1% fuel surcharge waiver
subject to applicable transaction limits and monthly cap.
Fuel should NOT be represented as a normal reward-earning category.
Paytm Gold Is Useful — But It Is Not Cash
The ₹1-per-point Paytm Gold redemption option is what makes the headline reward rates attractive.
But Paytm Gold is not the same as:
- statement cashback
- bank-account cashback
- fixed cash value held indefinitely
Digital gold value can move with gold prices.
So CardRecommend should distinguish:
effective Paytm Gold reward value
from:
direct cashback
Do NOT describe 1 RP = ₹1 as generic cash redemption.
Reddit Feedback: Use Only as Context
Recent cardholder discussions provide useful practical context.
Some cardholders report:
- roughly 2% effective Paytm UPI earning
- smooth approval experiences
- actual use of the flight-linked lounge benefit
Other users report:
- delays or confusion around Paytm Gold reward posting
- temporary app/card visibility issues
These are individual experiences only.
Do NOT:
- infer approval rates
- claim reward posting problems are widespread
- override issuer terms with Reddit screenshots
The useful practical advice is:
track Reward Point posting after large Paytm Gold or Paytm Travel transactions.
Paytm AU vs Kiwi
Kiwi is a genuinely relevant UPI alternative.
Kiwi's proposition is simpler because it focuses on direct/real UPI cashback rather than Paytm Gold-linked reward value.
Paytm AU is better suited if:
- Paytm is already your main UPI app
- many UPI purchases are smaller transactions
- you book travel through Paytm
- you use Paytm Gold
- family lounge access is useful
Kiwi is better suited if:
- you prefer simple cashback
- you do not want to redeem points into Paytm Gold
- you do not want your best rate tied to Paytm
- everyday UPI value matters more than travel benefits
Do NOT choose Paytm AU solely because:
“2% is higher than 1.5%”
The transaction-size structure, Paytm-app requirement and reward-redemption method matter. For users heavily in the Tata ecosystem, the Tata Neu Infinity HDFC Bank Credit Card offers a powerful alternative on RuPay UPI. You can test your spending profile in the CardRecommend Card Finder.
Who Should Apply?
Paytm AU makes sense if:
- Paytm is already your preferred UPI app
- you make frequent everyday merchant UPI transactions
- you book flights through Paytm
- you use or are comfortable with Paytm Gold
- you travel with family
- you want a lifetime-free RuPay card
The card can provide meaningful value without high annual spending if the user naturally fits the ecosystem.
Who Should Skip It?
Skip or deprioritise Paytm AU if:
- you mainly use Google Pay or PhonePe
- you want direct cashback
- you never use Paytm Gold
- you book flights directly with airlines
- you are interested only because you saw “12 lounge visits”
- your normal UPI usage does not fit the card's strongest reward structure
The card should fit existing behaviour.
Users should not redesign their spending merely to earn the advertised rewards.
CardRecommend Verdict
The Paytm AU Credit Card is one of the more interesting lifetime-free UPI cards in late 2026, but only if you understand what the headline percentages and lounge numbers actually mean.
The strongest everyday proposition is real:
up to 2% on eligible Paytm UPI spending
provided the transaction fits the applicable reward tier and the Reward Points are redeemed optimally through Paytm Gold.
The 5% Paytm Travel and Paytm Gold categories are also genuinely attractive, although the monthly reward caps prevent this from being an unlimited 5% product.
But the standout benefit is the family lounge structure.
And that benefit must be represented correctly.
You do not receive 12 unconditional lounge visits simply for owning Paytm AU.
You need an eligible round-trip Paytm flight booking, currently described by Paytm as at least ₹5,000, to unlock the family-lounge benefit.
Current launch material describes the programme as supporting multiple family members together and up to 12 visits annually.
That makes the card unusually good for one specific customer:
a Paytm-first UPI user who also books family travel through Paytm.
For that person, a lifetime-free card delivering up to 2% UPI value, 5% Paytm Travel/Gold value and booking-linked family lounge access is compelling.
For someone who uses another UPI app and books flights directly, the proposition becomes much more ordinary.
So I would apply:
if Paytm already sits at the centre of your payment and travel behaviour.
I would skip it:
if you need to change your behaviour merely to earn the advertised rewards.
The best credit card rewards transactions you already make.
Paytm AU does that well — but only for a Paytm-first user.
<div className="not-prose my-8 p-5 sm:p-6 rounded-2xl border border-orange-500/30 bg-[#070D1B] flex flex-col sm:flex-row items-start sm:items-center justify-between gap-4"> <div> <span className="text-[10px] uppercase font-bold tracking-widest text-[#FF5B00] block mb-1">APPLY & COMPARE</span> <h4 className="text-base sm:text-lg font-bold text-white">Ready to choose your UPI card?</h4> <p className="text-xs sm:text-sm text-slate-300">Apply directly on AU Small Finance Bank portal or evaluate side-by-side against Kiwi.</p> </div> <div className="flex flex-wrap items-center gap-3 w-full sm:w-auto"> <a href="/go/paytm-au-credit-card/" target="_blank" rel="noopener noreferrer" className="flex-1 sm:flex-none text-center px-5 py-2.5 rounded-xl bg-[#FF5B00] hover:bg-[#e05000] text-white font-bold text-xs transition">Apply for Paytm AU</a> <a href="/compare?cards=paytm-au-credit-card,pnb-kiwi-credit-card" className="flex-1 sm:flex-none text-center px-4 py-2.5 rounded-xl bg-[#121B2D] hover:bg-slate-800 text-slate-200 border border-slate-700 font-bold text-xs transition">Compare Paytm AU vs Kiwi</a> </div> </div>
Recommended Alternatives
PNB Kiwi Credit Card
Daily digital spenders, mobile UPI QR payments, and consumers looking for a lifetime free RuPay credit card with direct cashback conversion.
Tata Neu Infinity HDFC Bank Credit Card
Frequent shoppers across the Tata consumer ecosystem and digital spenders wanting maximum rewards on QR code merchant UPI payments.
Cards Discussed in This Review
Frequently Asked Questions
Is the Paytm AU Credit Card lifetime free?
Yes. The current AU proposition lists: ₹0 joining fee and: ₹0 annual fee.
Does Paytm AU give 2% rewards on every UPI transaction?
No. The highest published rate applies to eligible Paytm UPI transactions within the applicable lower transaction-size tier. The published rate falls to 1% above ₹2,000 and to 0.25% through other UPI apps.
Does Paytm AU give 5% on Paytm Travel?
Eligible Paytm Travel spending currently earns: 5 Reward Points per ₹100. At ₹1 per Reward Point through Paytm Gold redemption, that equals approximately: 5% effective value, subject to caps and eligibility.
Does Paytm AU give 5% on all gold purchases?
No. The accelerated category is specifically: Paytm Gold. Do not apply it to jewellery or other gold merchants.
Are the 12 lounge visits unconditional?
No. The family lounge proposition is tied to qualifying Paytm flight bookings. The current Paytm guidance describes an eligible ₹5,000+ round-trip flight booking as the trigger.
Can family members use the lounge benefit?
The current proposition specifically markets family lounge access and describes support for multiple family members together. Do not hardcode exact guest/family interpretation beyond what current issuer terms explicitly support.
Is the lounge benefit domestic or international?
Current Paytm material describes this as: domestic family lounge access. Do not label it as international lounge access.
What is one Reward Point worth?
Current AU proposition: ₹1/RP when redeemed for Paytm Gold and approximately: ₹0.50/RP through other applicable redemption routes.
Is there a monthly reward cap?
Current Paytm guidance lists three separate: 1,000 Reward Point monthly buckets for: UPI, Paytm/e-commerce, offline/POS. Do not collapse these into a generic cap without preserving the bucket structure.

Founder & Editor, CardRecommend
Founder & Editor of CardRecommend. Dedicated to researching credit card reward structures, fee waivers, airport lounge policies, and calculating real user value across Indian financial products.