Executive Summary
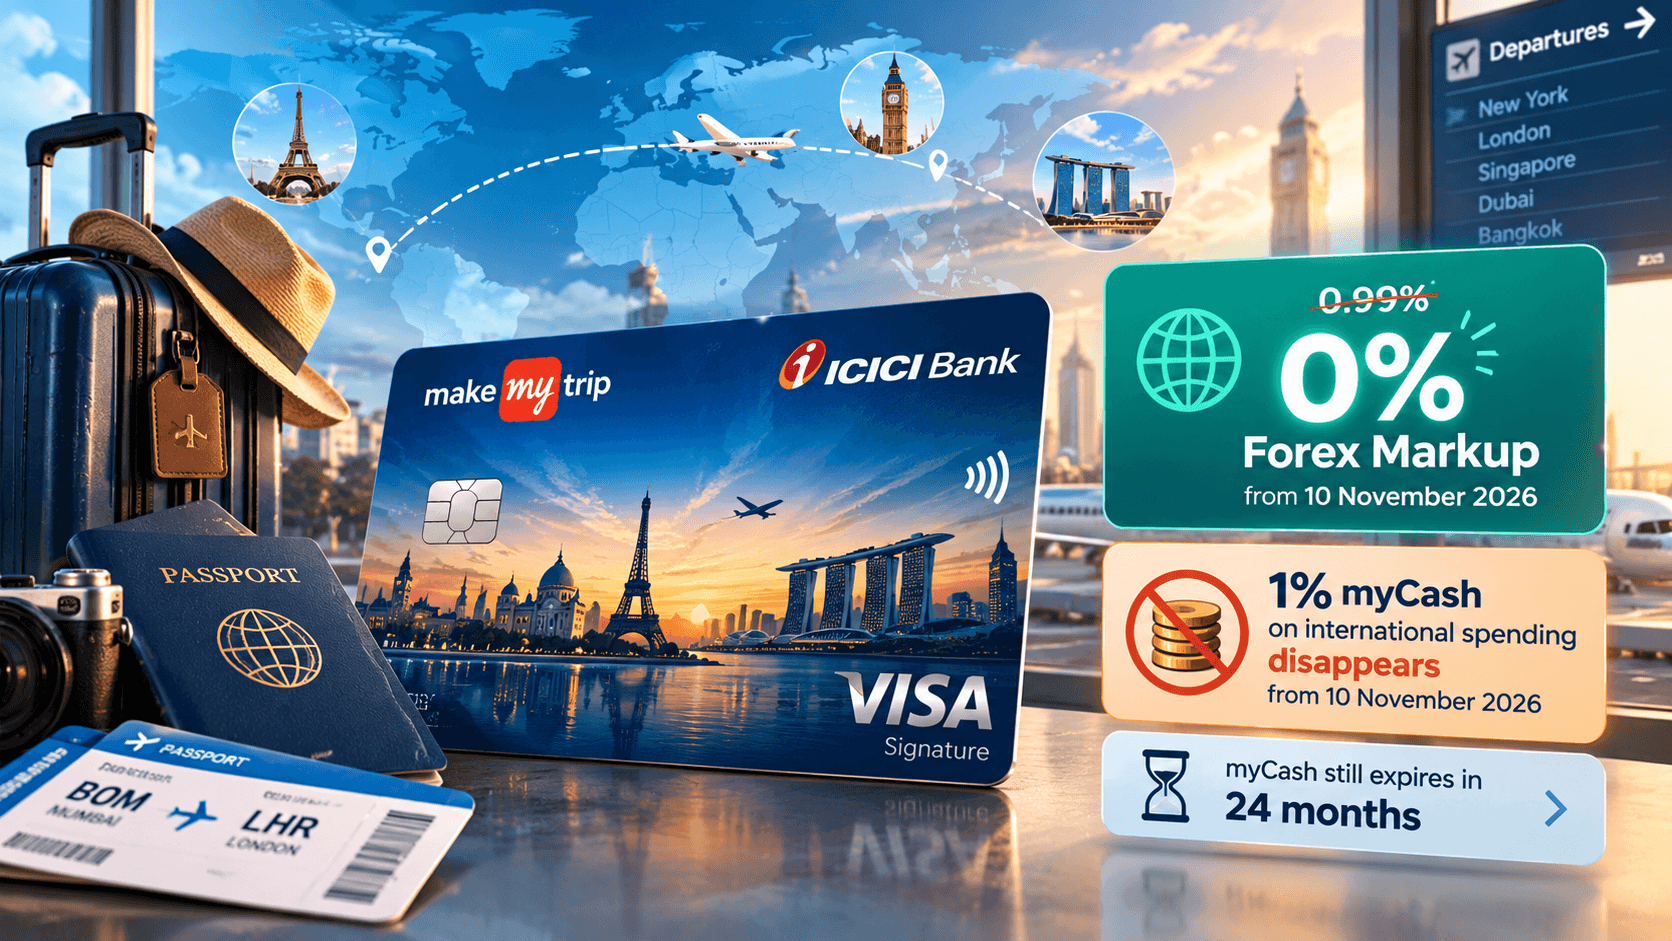
MakeMyTrip ICICI drops its 0.99% forex markup to zero from 10 November 2026. But international transactions outside MakeMyTrip will stop earning 1% myCash, and new myCash gets a 24-month expiry.
Featured Cards
MakeMyTrip ICICI Bank Signature Credit Card
Frequent domestic holidaymakers, hotel bookers, and flight travelers who regularly use MakeMyTrip for personal or family travel.
In This Guide
MakeMyTrip ICICI Goes Zero Forex From November 10 — But You Lose 1% myCash Abroad
The MakeMyTrip ICICI Bank Credit Card is about to become much more competitive for international spending.
But it is not a pure upgrade.
From 10 November 2026, ICICI Bank will reduce the card's forex markup from 0.99% to 0%.
At the same time, eligible international transactions outside MakeMyTrip will stop earning the 1% myCash they currently receive.
There is another devaluation arriving on the same date: newly earned myCash will no longer remain valid indefinitely. myCash credited from 10 November 2026 will expire after 24 months.
So the real change is:
Lower fees abroad, but no rewards on ordinary international spending and a new expiry clock on future myCash.
For travellers, that is still probably a net improvement.
But CardRecommend would not describe it simply as "MakeMyTrip ICICI now gives zero-cost international spending" without explaining what users are giving up.
Terms verified: 20 October 2026
The Short Answer
As of today, 20 October 2026, the MakeMyTrip ICICI Bank Credit Card still charges:
0.99% forex markup + applicable GST
It also currently earns 1% myCash on eligible international spending outside MakeMyTrip.
From 10 November 2026:
- forex markup falls to 0%
- ICICI's Dynamic Currency Conversion fee for this card also becomes 0%
- international transactions outside MakeMyTrip earn no myCash
- new myCash starts expiring after 24 months
- myCash earned before 10 November continues under the old no-expiry rule
The existing MakeMyTrip reward rates continue to include:
- 6% myCash on eligible hotel bookings
- 3% on eligible flights
- 3% on eligible holiday packages
- 3% on eligible cabs and buses
- ₹25 myCash per eligible train booking
- 1% on eligible domestic spends outside MakeMyTrip
ICICI's current terms value:
1 myCash = ₹1
Do Not Show 0% Forex as the Current Rate Yet
This matters for CardRecommend's database.
ICICI's current live product page still displays 0.99% forex markup, which is correct for transactions made before the new terms take effect.
The updated ICICI MITC separately states that:
no forex markup will be levied on the MakeMyTrip ICICI Bank Credit Card with effect from 10 November 2026.
The zero-forex change does not apply to the older MakeMyTrip ICICI Signature and Platinum cards.
So the correct timeline is:
| Period | Forex markup |
|---|---|
| Until 9 November 2026 | 0.99% |
| From 10 November 2026 | 0% |
This should be treated as a scheduled future change, not as a current benefit before the effective date.
International Rewards Are Being Removed at the Same Time
The biggest catch is hidden in the updated reward table.
ICICI's new card terms explicitly say:
International spends outside MakeMyTrip: No rewards from 10 November 2026.
Until then, the card's original proposition includes 1% myCash on eligible retail spending, including foreign transactions.
When ICICI launched the card, it marketed the combination of:
0.99% forex markup + 1% myCash on international transactions.
That combination disappears on 10 November.
The new proposition becomes:
0% forex + 0% myCash on ordinary international transactions.
Is That Actually Better?
Slightly, yes.
Suppose you spend the equivalent of ₹1 lakh abroad.
Before 10 November
Forex markup:
₹1,00,000 × 0.99% = ₹990
GST at 18% on the markup:
₹990 × 18% = ₹178.20
Total forex-related issuer cost:
₹1,168.20
Eligible myCash earned:
₹1,00,000 × 1% = ₹1,000 myCash
Since 1 myCash = ₹1, assuming you fully use the reward at face value:
₹1,168.20 fee - ₹1,000 reward = ₹168.20 net cost
From 10 November
Forex markup:
₹0
myCash on international spending outside MakeMyTrip:
₹0
Net issuer forex cost:
₹0
So purely on card economics, the new structure is better by roughly:
₹168 per ₹1 lakh of eligible international spending
assuming you previously valued every myCash at its full ₹1 face value.
That is an improvement.
But it is nowhere near as dramatic as moving from a conventional 3.5% forex card to zero forex.
MakeMyTrip ICICI Bank Credit Card
Explore complete card fees, reward rules, and upcoming zero-forex terms before you travel abroad.
The Change Is More Valuable If You Don't Fully Value myCash
The previous calculation assumes:
1 myCash = ₹1 of value to you personally.
Technically, that is the redemption rate.
But myCash is not cash in your bank account.
It is primarily useful through MakeMyTrip for eligible travel bookings.
If you rarely use MakeMyTrip, you may personally value ₹1,000 myCash at less than ₹1,000.
In that case, removing the 0.99% forex markup becomes more valuable than the simple ₹168-per-lakh calculation suggests.
For regular MakeMyTrip users, though, the old 1% reward was genuinely useful.
The Bigger Devaluation Is myCash Expiry
Until now, one of the card's strongest selling points was:
myCash rewards that did not expire under the existing treatment.
That changes for new rewards from 10 November 2026.
ICICI's updated terms state that myCash earned through the current MakeMyTrip ICICI card from that date will be valid for:
24 months
The good news is that the change is not retroactive.
ICICI explicitly says:
myCash earned before 10 November 2026 will continue to never expire after being credited to the MakeMyTrip wallet.
That distinction is important.
Existing myCash balance
Old no-expiry treatment continues.
myCash earned from 10 November onwards
Expires 24 months from the credit date.
For frequent travellers, two years is probably sufficient.
For occasional users accumulating myCash slowly, this is a meaningful downgrade.
The Card Is Also Losing ICICI's DCC Fee
There is another positive change that is easy to miss.
ICICI currently charges its own Dynamic Currency Conversion fee on relevant INR-denominated international transactions.
Its updated MITC states that from 10 November 2026, no ICICI Dynamic Currency Conversion fee will apply to the MakeMyTrip ICICI Bank Credit Card.
This does not mean you should start choosing INR at overseas merchants.
A merchant or overseas ATM can still offer its own Dynamic Currency Conversion rate, which may be worse than the Visa/Mastercard conversion.
So even after the card becomes zero forex:
Pay in the local currency abroad whenever possible.
The MakeMyTrip Reward Engine Is Otherwise Still Strong
The zero-forex change does not remove the card's core MakeMyTrip earning structure.
Current updated terms show:
| Spend category | myCash |
|---|---|
| MakeMyTrip hotels | 6% |
| MakeMyTrip flights | 3% |
| MakeMyTrip holiday packages | 3% |
| MakeMyTrip cabs | 3% |
| MakeMyTrip buses | 3% |
| MakeMyTrip trains | ₹25 per booking |
| Eligible domestic spends outside MMT | 1% |
| International spends outside MMT from Nov 10 | 0% |
The accelerated MakeMyTrip categories remain the main reason to own the card.
This remains fundamentally a MakeMyTrip travel card, rather than becoming a pure zero-forex product.
What Happens to International MakeMyTrip Bookings?
This distinction matters.
The new exclusion says:
international spends outside MakeMyTrip
earn no rewards.
The MakeMyTrip booking categories themselves remain separately listed at their accelerated reward rates.
That means an eligible international flight or hotel purchased through MakeMyTrip should continue to follow the relevant MakeMyTrip earning structure rather than the zero-reward outside-MMT category, subject to final transaction eligibility under ICICI's terms.
Do not interpret the November change as:
"Anything international earns zero."
The restriction is specifically on international spending outside MakeMyTrip.
Lounge Access Remains Useful, but Spend-Gated
The MakeMyTrip ICICI card currently gives the primary cardholder:
- 2 complimentary domestic airport lounge visits per quarter
- domestic lounge eligibility after ₹75,000 of spending in the preceding quarter
- 1 complimentary international lounge visit per calendar year
That gives the card a genuine travel benefit beyond zero forex.
But the ₹75,000 quarterly spend requirement makes the domestic lounge benefit less compelling for low spenders.
The ₹999 Fee Still Matters
The standard annual fee is:
₹999 + GST
ICICI currently waives the subsequent annual fee when the cardholder spends ₹3 lakh or more in the previous anniversary year.
If the annual fee is charged, the cardholder receives a ₹1,000 MakeMyTrip hotel voucher under the existing renewal-benefit terms.
For someone who can genuinely use the ₹1,000 hotel voucher, the annual-fee economics are not particularly difficult.
For someone who barely uses MakeMyTrip, paying an annual fee purely for zero forex is harder to justify because lifetime-free zero-forex alternatives exist.
MakeMyTrip ICICI vs Scapia After November 10
This MakeMyTrip ICICI vs Scapia comparison becomes much more interesting after the change.
Both cards will offer:
0% forex markup
and both effectively provide:
no rewards on ordinary forex transactions
because Scapia also excludes forex transactions from earning Scapia Coins.
Choose MakeMyTrip ICICI if:
- you regularly book through MakeMyTrip
- 6% hotel and 3% flight rewards are valuable to you
- you can use MMTBLACK benefits
- you value its lounge proposition
- you can use the ₹1,000 renewal hotel voucher
Choose Scapia if:
- you want a lifetime-free card
- you do not want to track a ₹3 lakh annual fee-waiver requirement
- you prefer Scapia's broader travel ecosystem
- you can use its domestic airport privileges
- you value its eligible domestic rewards
On ordinary international card spending itself, the products become much more similar after 10 November:
zero forex, no foreign-spend rewards.
IDFC FIRST WOW! Still Has One Important Advantage
If your primary objective is international spending rather than MakeMyTrip travel rewards, IDFC FIRST WOW! remains a stronger pure foreign-transaction proposition for someone comfortable with a secured card.
FIRST WOW! currently offers:
- 0% forex
- zero joining and annual fee
- up to 4 Reward Points per ₹200 on eligible international spending
- ₹0.25 value per Reward Point
That works out to roughly:
0.5% nominal reward value
on eligible international transactions on top of zero forex.
The catch is that WOW! is FD-backed.
So from 10 November:
MakeMyTrip ICICI: 0% forex + no outside-MMT international rewards
FIRST WOW!: 0% forex + rewards on eligible international transactions
For someone who only cares about spending abroad and is comfortable locking money in an FD, WOW! has stronger transaction economics.
ixigo AU Is Another Relevant Alternative
The ixigo AU Credit Card also offers:
- lifetime-free pricing
- zero forex markup
- travel-oriented benefits
- lounge access under the applicable current terms
But international transactions themselves do not earn normal reward points under the current zero-forex structure.
So its foreign-spend economics look more like the future MakeMyTrip ICICI:
zero forex + no rewards on ordinary foreign transactions
The decision then comes down to which travel ecosystem and benefits you actually use.
Reddit Reaction Gets the Trade-Off Mostly Right
Current Indian credit-card discussions are focusing on the right questions.
Some users see zero forex as a major improvement and a stronger challenge to Scapia and other travel cards.
Others point out that the card is simultaneously losing:
- 1% international myCash
- no-expiry treatment for future myCash
- some of the simplicity of its old proposition
There is also understandable criticism that some competing zero-forex cards are lifetime free, while MakeMyTrip ICICI carries a standard ₹999 annual fee.
Reddit should be used only for sentiment and practical questions.
Official ICICI documentation controls all financial facts.
Should Existing Cardholders Change Their Spending Before November 10?
There is no reason to manufacture international spending before the change.
Yes, eligible international transactions currently earn 1% myCash.
But you are also paying 0.99% forex markup plus GST on the markup.
The reward mostly offsets the issuer cost rather than creating a meaningful profit.
From 10 November, the structure becomes simpler:
no forex markup, no outside-MMT international reward.
For most travellers, I would prefer the simpler future structure.
What Should Existing Users Do With Their myCash?
There is no reason to rush and redeem existing myCash merely because the terms are changing.
ICICI says myCash earned before 10 November 2026 will retain its existing no-expiry treatment.
Only myCash earned from 10 November onwards gets the new 24-month validity.
So users should distinguish between:
old balance: no expiry
and:
new earnings: 24-month expiry
CardRecommend's canonical data should preserve that date distinction if reward-expiry history is supported.
Should You Apply for MakeMyTrip ICICI After This Change?
The card becomes more attractive for one specific customer:
someone who already uses MakeMyTrip and also travels internationally.
You get:
- 0% forex from 10 November
- 6% myCash on eligible MakeMyTrip hotel bookings
- 3% on eligible flights, holiday packages, cabs and buses
- 1% on eligible domestic spending outside MMT
- RuPay/UPI usefulness where applicable
- domestic and international lounge privileges
- MMTBLACK benefits
- a ₹1,000 renewal hotel voucher when the fee is charged under applicable terms
That is a strong travel-focused package for ₹999 + GST.
But if all you want is zero forex, I would not automatically choose it.
Scapia and ixigo AU provide zero-forex alternatives without a standard annual fee.
FIRST WOW! currently goes one step further by rewarding eligible international transactions, although it requires an FD.
Zero forex alone is no longer enough to make a travel credit card distinctive.
CardRecommend Verdict
The MakeMyTrip ICICI Bank Credit Card gets better for international travellers on 10 November 2026 — but this is a trade-off, not a free upgrade.
Removing the 0.99% forex markup and ICICI's DCC fee is genuinely useful.
For a ₹1 lakh eligible overseas spend today, the card effectively charges around ₹1,168 in forex markup plus GST while earning roughly ₹1,000 myCash.
From 10 November:
the fee falls to zero and the reward also falls to zero.
That is still better.
It removes the cash charge rather than giving you a restricted reward to approximately offset it.
But the more disappointing change is the new 24-month expiry on myCash earned from 10 November onwards.
One of this card's cleaner advantages was that rewards did not expire under the existing treatment. That is now being weakened for future earnings.
So my recommendation is:
Keep or apply for MakeMyTrip ICICI if you genuinely use MakeMyTrip and want one card combining strong MakeMyTrip earn rates, lounge benefits and zero forex.
Do not choose it solely because it becomes zero forex.
Scapia and ixigo AU offer the same headline foreign-spend fee at lifetime-free pricing, while FIRST WOW! currently goes one step further by rewarding eligible international spending.
The most important timing point for CardRecommend readers is simple:
Until 9 November 2026, the forex rate is still 0.99%.
From 10 November 2026, it becomes 0%.
Do not confuse an announced future benefit with the card's current terms.
MakeMyTrip ICICI Bank Credit Card
Keep or apply if you actively use MakeMyTrip for travel and want travel rewards combined with zero forex from 10 November 2026.
Recommended Alternatives
Scapia Axis Bank Credit Card
Zero Forex Markup, Scapia Travel Rewards & RuPay UPI
IDFC FIRST WOW! Credit Card
Credit builders, students, freelancers without income proof, and overseas travelers seeking a guaranteed-approval card with zero foreign exchange fees and high FD interest.
ixigo AU Credit Card
Budget International Travelers, Train & Flight Bookers, Online Shoppers & UPI Commuters
Cards Discussed in This Article
IDFC FIRST WOW! Credit Card
ixigo AU Credit Card
Frequently Asked Questions
Is the MakeMyTrip ICICI Credit Card zero forex today?
No.
As of 20 October 2026, the current forex markup remains:
0.99% + applicable GST
Zero forex becomes effective on 10 November 2026.
When does MakeMyTrip ICICI become zero forex?
ICICI Bank's updated terms state that no forex markup will apply from:
10 November 2026
Will MakeMyTrip ICICI earn rewards on international spending after November 10?
Ordinary international spending outside MakeMyTrip will earn:
no myCash from 10 November 2026
Do MakeMyTrip bookings still earn myCash?
Yes.
Current terms continue to list accelerated rewards including:
- 6% on eligible hotels
- 3% on eligible flights
- 3% on eligible holiday packages
- 3% on eligible cabs and buses
subject to applicable terms.
Will existing myCash expire after the change?
No.
myCash earned before 10 November 2026 keeps its existing no-expiry treatment.
myCash earned from 10 November onwards receives a 24-month validity.
Is the DCC fee also removed?
ICICI's updated MITC states that its Dynamic Currency Conversion fee for the current MakeMyTrip ICICI Bank Credit Card becomes 0% from 10 November 2026.
You should still generally select local currency abroad because merchants or overseas ATMs may apply their own conversion rates.
Does zero forex also apply to the old MakeMyTrip Signature and Platinum cards?
No.
The new zero-forex treatment applies to the current MakeMyTrip ICICI Bank Credit Card and should not be applied to the legacy Signature and Platinum variants.
Is MakeMyTrip ICICI better than Scapia after November 10?
For ordinary foreign transactions, both effectively offer:
0% forex + no rewards on forex spending
MakeMyTrip ICICI makes more sense for users who heavily use MakeMyTrip.
Scapia has the advantage of lifetime-free pricing and a different domestic travel-rewards ecosystem.

Founder & Editor, CardRecommend
Founder & Editor of CardRecommend. Dedicated to researching credit card reward structures, fee waivers, airport lounge policies, and calculating real user value across Indian financial products.