Executive Summary
IDFC FIRST Bank's zero-forex move has removed one of Scapia's biggest differentiators. Scapia still has a case, but mainly for its domestic travel rewards, UPI earning and airport privileges — not for foreign spending alone.
Cards Compared
Scapia Axis Bank Credit Card
Zero Forex Markup, Scapia Travel Rewards & RuPay UPI
IDFC FIRST WOW! Credit Card
Credit builders, students, freelancers without income proof, and overseas travelers seeking a guaranteed-approval card with zero foreign exchange fees and high FD interest.
IDFC FIRST Wealth Credit Card
High-income earners, corporate executives, and global travelers looking for comprehensive airport lounge and golf privileges without paying recurring annual credit card maintenance fees.
In This Guide
IDFC FIRST Bank has taken away one of Scapia’s easiest selling points.
Until recently, “zero forex” was enough to make Scapia an obvious card to consider before an international trip. In September 2026, IDFC FIRST Bank extended 0% forex markup across its entire credit-card portfolio, including existing cards. The bank formally announced the change on 17 September; contemporaneous reporting dates the rollout to 9 September 2026.
That does not make Scapia irrelevant. But it changes the reason to apply.
For a traveller choosing a card primarily for overseas spending in late 2026, Scapia is no longer the automatic answer simply because it charges zero forex. Its case now depends on everything around the foreign transaction itself: domestic rewards, Scapia travel-booking rewards, RuPay/UPI utility and spend-linked domestic airport privileges.
There is another important catch: Scapia does not award Scapia Coins on forex transactions. So on the overseas purchase itself, you get the benefit of zero forex but no reward on top.
Terms verified: 16 October 2026
Is Scapia Still Worth Getting?
Yes, but I would no longer get Scapia purely for zero forex.
Scapia remains a strong lifetime-free travel card if you also value its effective 2% travel value on eligible Visa/Mastercard domestic spending, 4% travel value on eligible Scapia-app bookings, RuPay/UPI earning and unlimited domestic lounge/airport privileges after meeting the ₹20,000 monthly spend requirement.
If your only objective is to spend abroad without forex markup, IDFC FIRST has substantially weakened the reason to open another card.
And if you are comfortable blocking money in an FD, IDFC FIRST WOW! is actually stronger than Scapia on the foreign transaction itself right now: it combines 0% forex with up to 4X reward points on eligible international spending.
That distinction matters.
0% forex + no rewards is not the same product as 0% forex + rewards.
Scapia Axis Bank Credit Card
Scapia remains one of India's few lifetime-free travel cards combining 0% forex markup with up to 2% domestic travel value, 4% travel booking value and spend-linked domestic lounge privileges.
What IDFC FIRST Actually Changed
IDFC FIRST Bank now states that all of its credit cards carry zero forex markup, covering cards ranging from Classic, Millennia, Select and Wealth to WOW!, Ashva, Mayura and the bank’s other current variants. The benefit applies without requiring an international-spend threshold.
This matters for Scapia because millions of people do not necessarily need a dedicated travel card anymore just to eliminate the usual foreign-currency markup.
If you already hold a suitable IDFC FIRST card, your existing card may now solve the forex problem.
But there is an important reward complication for anyone travelling after 26 October 2026.
IDFC FIRST’s broad September announcement said rewards or cashback would continue “as applicable” on international transactions. However, current individual product pages for cards including FIRST Wealth, FIRST Classic and FIRST Millennia explicitly state that international transactions will stop earning Reward Points from 26 October 2026.
For a late-2026 traveller, I would therefore use the current card-specific terms, not the earlier general announcement. (See CardRecommend's detailed IDFC FIRST zero forex analysis for earlier rollout documentation).
FIRST WOW! is different. Its current product page still explicitly advertises zero forex with 4X Reward Points on international spends.
That is why comparing “Scapia vs IDFC FIRST” as if IDFC FIRST were one card would be misleading.
The Biggest Scapia Catch: Forex Transactions Earn No Scapia Coins
This is the part I would understand before applying.
Scapia charges 0% forex markup, but its current rewards documentation explicitly lists forex transactions among transactions that do not earn Scapia Coins.
Suppose you spend ₹1 lakh equivalent during an international trip.
With Scapia:
₹1,00,000 foreign spend
Forex markup: ₹0
Scapia Coins earned on that forex spend: ₹0
That is still significantly better than paying a conventional 3%–3.5% forex markup.
But zero forex is now available elsewhere.
Once another card also gives you 0% markup, the next question becomes:
What do I earn after the markup is removed?
That is where IDFC FIRST WOW! creates a problem for Scapia.
Scapia vs IDFC FIRST WOW! vs FIRST Wealth
These are the two IDFC FIRST cards I think actually help answer the Scapia decision.
FIRST WOW! matters because it combines zero forex and international rewards at no annual fee, although it requires a fixed deposit.
FIRST Wealth matters because it is an unsecured lifetime-free premium card with genuine international lounge access, although its official page says international reward points will stop from 26 October 2026 and its current published income eligibility is ₹36 lakh annually.
| Feature | Scapia | IDFC FIRST WOW! | IDFC FIRST Wealth |
|---|---|---|---|
| Joining fee | ₹0 | ₹0 | ₹0 |
| Annual fee | ₹0 | ₹0 | ₹0 |
| Forex markup | 0% | 0% | 0% |
| Rewards on eligible international spend | No | Yes — up to 4X | No from 26 Oct 2026 |
| Effective international reward value | 0% | About 0.5% at stated ₹0.25/RP value | 0% after 26 Oct |
| Security/FD required | No | Yes, minimum ₹20,000 FD | No |
| General eligible domestic rewards | 10% Scapia Coins on Visa/Mastercard = about 2% travel value | 4X = about 0.5% value | 3X on general eligible spends; accelerated categories differ |
| Scapia/in-app travel earn | 20% Scapia Coins = about 4% travel value | Bonus rewards on eligible IDFC app travel bookings | Bonus rewards on eligible IDFC app travel bookings |
| UPI option | RuPay available; 5% Scapia Coins on eligible ₹500+ transactions = about 1% travel value | Optional Digital UPI card with separate fee | Optional UPI card structure |
| Domestic airport privileges | Unlimited domestic lounge/airport privileges after ₹20,000 qualifying monthly spend | No comparable regular WOW lounge proposition | 1 domestic lounge visit/quarter after spend condition |
| International lounge | No conventional international lounge benefit | No conventional regular WOW lounge benefit | 1 global lounge visit/quarter after spend condition |
| Reward expiry | Scapia Coins valid 3 years | 24 months | 24 months |
| Redemption | Primarily inside Scapia travel ecosystem | FIRST Rewards ecosystem; redemption fee applies | FIRST Rewards ecosystem; redemption fee applies |
Scapia currently values 5 Scapia Coins at ₹1. That means its advertised 10% Visa/Mastercard earning translates into roughly 2% usable travel value, its 5% RuPay earning translates to roughly 1%, and its 20% Scapia-app earning translates into roughly 4% travel value. Coins can be used for eligible flights, hotels, trains, buses, visas, experiences and other Scapia-app products and are currently valid for three years.
FIRST WOW!, meanwhile, currently gives up to 4 Reward Points per ₹200 on international and eligible domestic spending. With IDFC FIRST valuing each point at ₹0.25, that works out to:
₹200 spend → 4 Reward Points → ₹1 value
or roughly:
0.5% reward value
IDFC FIRST charges ₹99 plus GST per reward redemption, so small redemptions can reduce the practical return.
On ₹1 Lakh of Overseas Spending, FIRST WOW! Currently Beats Scapia
This is the cleanest example of how the market has changed.
Scapia
₹1,00,000 international spend
Forex markup: ₹0
Scapia Coins: ₹0
Net reward value from the transaction: ₹0
IDFC FIRST WOW!
₹1,00,000 international spend
At 4 Reward Points per ₹200:
₹1,00,000 ÷ ₹200 = 500 earning units
500 × 4 = 2,000 Reward Points
2,000 × ₹0.25 = ₹500 nominal reward value
Forex markup: ₹0
So FIRST WOW! currently gives roughly ₹500 of reward value on ₹1 lakh of eligible international spending, before accounting for its ₹99 + GST redemption charge.
That is not a huge return.
But ₹500 is still better than zero.
The trade-off is that WOW! is FD-backed, with IDFC FIRST currently requiring a minimum ₹20,000 fixed deposit.
If you do not want to lock money into an FD, the comparison changes.
FIRST Wealth Doesn't Beat Scapia on Forex Rewards After 26 October — But It Does on International Lounges
FIRST Wealth is more interesting for a different reason.
It is lifetime free and now carries zero forex. But the current Wealth page explicitly says:
international transactions will stop earning Reward Points from 26 October 2026.
For an overseas purchase after that date, its basic economics therefore look much like Scapia:
0% forex + no international reward points.
But Wealth gives something Scapia does not: true international lounge access.
The current benefit is one complimentary domestic lounge visit and one global lounge visit per quarter, with the lounge benefit activated for the following month after spending ₹20,000 in the current calendar month.
Scapia gives much stronger domestic airport flexibility, but it does not currently provide conventional international lounge access.
That distinction is important for someone choosing a card specifically for international travel.
Scapia's Airport Benefit Is Still Better Than It First Looks — Domestically
Scapia requires ₹20,000 of qualifying spend in a billing cycle to unlock its domestic Airport Privileges on the next statement date. Once eligible, the programme includes unlimited domestic lounge access and can also be used for eligible dining, shopping or spa benefits at participating Indian airports.
For someone flying domestically several times a year, this can be substantially more useful than a card offering one or two visits every quarter.
But Scapia's so-called international Airport Privileges should not be confused with international lounge access.
If you book an international flight worth at least ₹50,000 in a single booking through the Scapia app, Scapia currently offers up to ₹2,000 back in Scapia Coins on eligible dining or shopping at international departure terminals in India.
That can be useful.
It is not the same thing as a Priority Pass or global lounge benefit abroad.
For a frequent international traveller, FIRST Wealth's genuine global lounge visits may therefore matter more.
Scapia Is Still Much Better for Domestic Everyday Rewards
This is where Scapia survives the IDFC zero-forex change.
On eligible everyday spending:
- Scapia Visa and the Axis Mastercard variant earn 10% rewards in Scapia Coins.
- Scapia RuPay earns 5% rewards on eligible ₹500+ transactions.
- Eligible Scapia-app travel purchases earn 20% rewards.
Because 5 Scapia Coins equal ₹1, the effective values are roughly:
Visa/Mastercard: 2% travel value
RuPay: 1% travel value
Scapia-app travel bookings: 4% travel value
These are substantially more compelling domestic earn rates than simply using FIRST WOW! at its standard 4X structure.
So the right way to think about Scapia in late 2026 is not:
“This is my zero-forex card.”
It is:
“This is a no-fee domestic travel-rewards card that also happens to charge zero forex when I travel.”
That is a stronger and more accurate reason to own it.
Scapia Now Has Three Issuer Options
Scapia's issuer situation has also changed in 2026.
Current official material shows Scapia co-branded cards with:
Axis Bank
The Scapia Axis Bank Credit Card launched on 3 September 2026. Axis currently offers Mastercard and RuPay Scapia cards with zero joining fee, zero annual fee and zero forex markup. Its Mastercard earns 10% Scapia Coins on eligible everyday spending, while the RuPay card earns 5% on eligible ₹500+ spending.
Federal Bank
The current Federal version uses a dual-line setup: Visa and RuPay cards share one credit limit and appear on one statement. Visa handles the stronger everyday earning structure and international use, while RuPay adds credit-on-UPI utility.
BOBCARD
With the BOBCARD version, applicants currently choose either Visa or RuPay rather than receiving the Federal dual-line arrangement.
For someone specifically wanting Scapia, having three issuer options is now a genuine advantage because your application is no longer tied to a single banking partner.
Approval, however, remains subject to issuer underwriting.
Recent Reddit discussions contain users reporting repeated Scapia application rejections despite apparently healthy credit profiles, while other travellers have shifted their attention to IDFC after its zero-forex move. Those are useful indications of user frustration, not reliable approval-rate statistics.
The Reward Restrictions Still Matter
Scapia's headline reward rates apply only to eligible spending.
Current Scapia documentation excludes categories including:
- Forex transactions
- Fuel
- Rent
- EMI transactions
- Wallet loading
- Education and school fees
- Insurance
- Crypto transactions
- Gift cards
- ATM cash withdrawals
Transaction thresholds also apply: Visa rewards generally require a transaction of at least ₹20, while RuPay earning generally requires ₹500 or more.
The most important exclusion for this article remains forex itself.
A person can spend extensively abroad with Scapia and save money on markup, but those overseas transactions are not building the Scapia Coin balance.
Redemption Is Also a Philosophical Difference
Scapia gives you relatively strong earn rates, but the value is intentionally tied to its ecosystem.
Scapia Coins can currently be redeemed inside the app for flights, hotels, trains, buses, visas, experiences and travel-related shopping, and Scapia allows users to cover up to 100% of an eligible booking using Coins. The current validity period is three years from earning.
That works well if you travel.
It is less attractive if what you really want is statement cashback.
IDFC FIRST reward points have broader Rewards Gallery-style redemption, but the bank currently charges a ₹99 + GST redemption convenience fee on cards such as WOW! and Wealth, and points on these cards are generally valid for 24 months under current terms.
Neither system is universally better.
Scapia is simpler if you are happy turning rewards back into travel.
RuPay and UPI Are a Real Remaining Advantage for Scapia
Scapia's RuPay card gives 5% rewards in Scapia Coins on eligible transactions of ₹500 or more, equivalent to roughly 1% travel value at the current conversion rate.
Federal's dual-line implementation is particularly convenient because the Visa and RuPay cards share one limit and one statement.
Axis also offers Scapia on Mastercard and RuPay, while BOBCARD applicants can choose the network they want.
IDFC FIRST also supports credit-card UPI through digital RuPay products, but on several core cards that involves a separate digital-card structure and fee.
If you want one travel ecosystem that also rewards merchant UPI spending, Scapia's implementation remains more compelling.
What Reddit Users Are Actually Asking After the IDFC Change
The clearest signal from recent Indian credit-card discussions is not that everybody suddenly dislikes Scapia.
It is that travellers are now asking whether they need it at all.
One recent r/CreditCardsIndia user said they were almost finished applying for Scapia for an international trip before discovering that IDFC cards had moved to zero forex, then asked whether FIRST Wealth made more sense. Other discussions similarly frame Scapia as worthwhile when its travel perks are useful, but question the need for another card when an existing IDFC card already handles foreign spending at 0% markup.
That is exactly the right question.
The answer depends on whether you are buying a forex feature or the whole Scapia travel product.
What About ixigo AU?
The ixigo AU Credit Card remains one of the strongest genuine alternatives.
It is currently lifetime free and carries zero forex markup. Its present proposition also includes domestic airport and railway lounge access plus one international lounge visit per year.
But there is an important similarity with Scapia.
AU Small Finance Bank's reward terms specifically state that international transactions do not earn Reward Points on the ixigo AU card.
So for overseas transactions:
Scapia: 0% forex + no rewards
ixigo AU: 0% forex + no rewards
The reason to choose ixigo AU is therefore its own travel-discount and lounge proposition, especially if you want some international lounge access, rather than a higher reward rate on the foreign purchase.
What About Niyo?
Niyo remains relevant mainly for users comfortable with secured/FD-backed products and a travel-first app.
Its current zero-forex page advertises an FD-backed credit card with 1% valueback on eligible international online spending, alongside higher valueback rates for selected domestic online and Niyo travel transactions.
The important word is online.
I would not treat that as a blanket 1% reward on every overseas card swipe.
Niyo can still make sense for someone specifically comfortable with the FD-backed model, but it is not the obvious replacement for Scapia for everybody.
Apply for Scapia
Apply for Scapia if you want more than zero forex.
It still makes sense if you:
- regularly spend on eligible domestic categories and can use the roughly 2% Visa/Mastercard travel value
- book flights, hotels and other travel through Scapia and can use the roughly 4% travel-booking value
- want RuPay/UPI earning
- can naturally meet the ₹20,000 monthly spend requirement for domestic Airport Privileges
- want unlimited qualifying domestic lounge access rather than a small quarterly allocation
- want a lifetime-free card
- are happy redeeming your rewards back into travel
In that situation, IDFC FIRST going zero forex does not destroy Scapia's value.
It merely removes one feature that used to make the decision much easier.
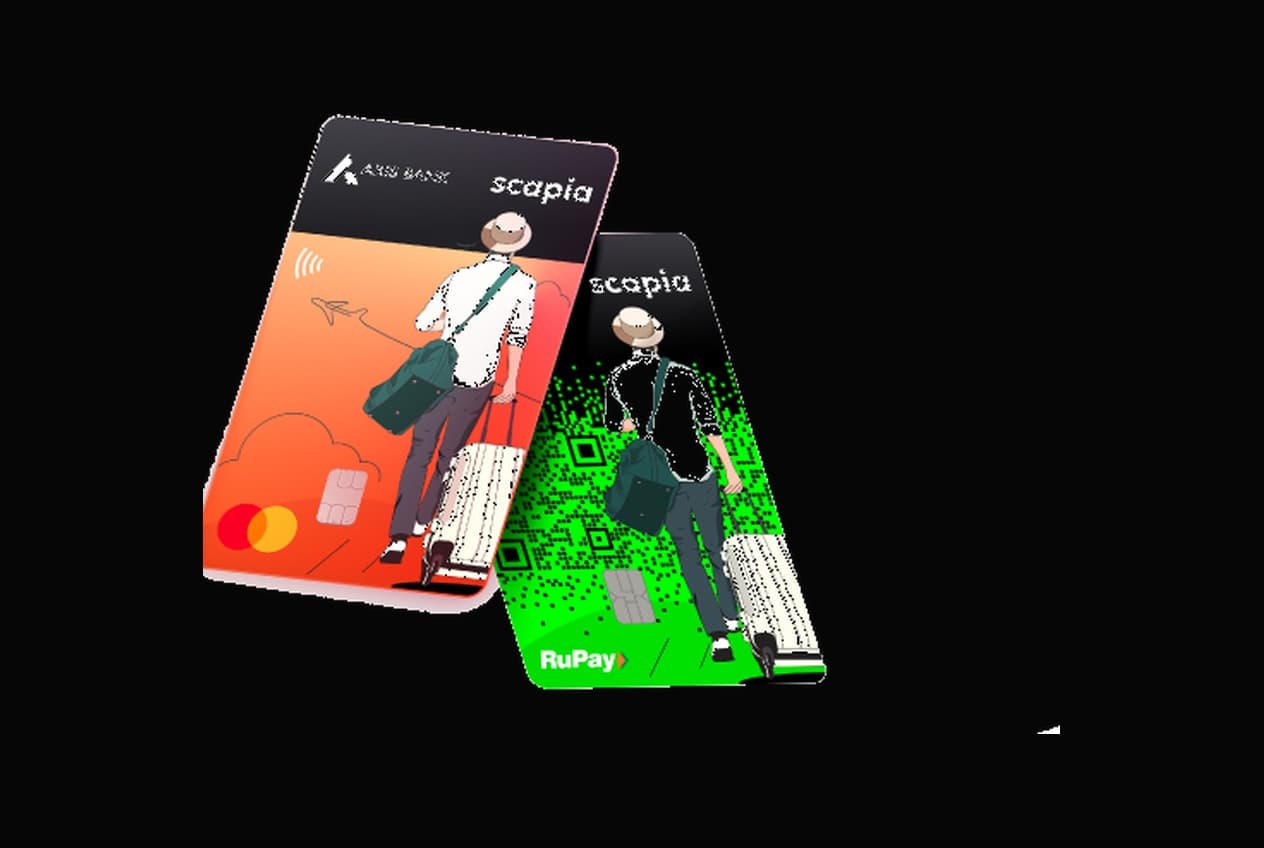
Scapia Axis Bank Credit Card
Scapia still makes sense if you want its domestic travel rewards, RuPay/UPI earning and spend-linked Airport Privileges — not just zero forex.
Skip Scapia
Skip Scapia if your main objective is simply to get a card for foreign spending.
Especially skip a new application if:
- you already hold an IDFC FIRST credit card with 0% forex and do not care about Scapia's domestic ecosystem
- you are comfortable using FIRST WOW! with an FD and want rewards on eligible overseas purchases as well as zero forex
- you qualify for FIRST Wealth and value genuine international lounge access more than unlimited domestic Scapia privileges
- you want cashback rather than travel-only reward redemption
- you will not reach Scapia's ₹20,000 monthly airport-privilege threshold
- you rarely book travel through the Scapia app
Zero forex by itself is no longer a sufficient reason to add Scapia to your wallet.
Compare Zero-Forex Alternatives
If your primary goal is international transactions without foreign currency markup, compare IDFC FIRST WOW!, Wealth, and ixigo AU.
Key Zero-Forex Credit Cards Compared
Review verified annual fees, foreign currency markup rates, reward points and airport lounge privileges.
CardRecommend Verdict
Scapia is still worth applying for in late 2026 — but I would no longer recommend it as a pure forex card.
IDFC FIRST Bank's portfolio-wide move to zero forex has substantially weakened Scapia's original international-spending advantage.
If your requirement is simply:
“I am travelling abroad and don't want to pay forex markup”
then first check what you already hold.
If you already have an IDFC FIRST card with zero forex, opening Scapia only for your foreign transactions is difficult to justify.
If you are willing to open an FD, FIRST WOW! is currently the stronger pure overseas-spend proposition because the bank's current terms combine 0% forex with up to 4X Reward Points on eligible international spending. Scapia gives 0% forex but no Scapia Coins on those transactions.
If you qualify for FIRST Wealth, it becomes attractive for travellers who care about genuine global lounge access, although its international reward points are currently scheduled to disappear from 26 October 2026.
But Scapia still has a reason to exist.
Its effective 2% travel value on eligible Visa/Mastercard domestic spending, roughly 4% on Scapia travel bookings, RuPay/UPI earning and unlimited spend-linked domestic airport privileges make it a more complete travel-rewards product than most zero-forex cards.
So my decision would be:
Choose Scapia if you want a travel ecosystem that you will also use heavily in India.
Choose IDFC FIRST WOW! if your priority is zero forex plus rewards on eligible international transactions and you are comfortable with an FD.
Choose FIRST Wealth if you qualify and international lounge access matters more than earning rewards on overseas spends after 26 October.
Skip a new Scapia application if zero forex is the only reason you wanted it.
Zero forex has become a feature.
Scapia now has to win on everything else.
Still unsure which card fits your profile? Use the CardRecommend Card Finder to calculate your net returns across domestic, international and UPI spending.
Apply for Scapia or Compare Head-to-Head
If you want a complete travel-rewards card for domestic spending, UPI and unlimited lounge privileges, apply for Scapia. If foreign currency spend is your only focus, compare zero-forex alternatives.
Recommended Alternatives
ixigo AU Credit Card
Budget International Travelers, Train & Flight Bookers, Online Shoppers & UPI Commuters
YES BANK Niyo Credit Card
International holidaymakers, digital nomads, study-abroad students, and global business travelers looking to eliminate the standard 3.5% foreign transaction fee.
Cards Compared in This Article
IDFC FIRST WOW! Credit Card
IDFC FIRST Wealth Credit Card
ixigo AU Credit Card
Frequently Asked Questions
Is Scapia still worth it after IDFC FIRST introduced zero forex?
Yes, but primarily for its broader travel ecosystem rather than zero forex alone. Scapia still offers strong eligible domestic earning, higher Scapia-app travel rewards, RuPay/UPI rewards and spend-linked domestic Airport Privileges. For pure foreign spending, there are now stronger or equally good alternatives.
Does Scapia earn rewards on international transactions?
No. Scapia's current rewards documentation explicitly excludes forex transactions from earning Scapia Coins. The card still charges zero forex markup.
Do all IDFC FIRST credit cards now have zero forex markup?
Yes. IDFC FIRST Bank's current zero-forex page states that zero forex markup applies across its credit-card portfolio.
Do IDFC FIRST credit cards earn rewards on international spending?
It depends on the card and date. Current pages for FIRST Wealth, Classic and Millennia say international transactions will stop earning Reward Points from 26 October 2026. FIRST WOW!'s current page, however, explicitly continues to advertise up to 4X Reward Points on international spending with zero forex markup.
Is IDFC FIRST WOW! better than Scapia for foreign spending?
For the international transaction itself, currently yes, assuming you are comfortable with its FD-backed structure. Both offer zero forex, but FIRST WOW! currently offers up to 4X Reward Points on eligible international spending while Scapia gives no Scapia Coins on forex transactions.
Does Scapia offer international lounge access?
Scapia's current proposition does not provide a conventional recurring global lounge benefit comparable with FIRST Wealth or Priority Pass-style access. Its international Airport Privileges instead provide up to ₹2,000 back in Scapia Coins on eligible shopping or dining at international terminals in India after qualifying ₹50,000 international-flight bookings through Scapia.
Scapia or ixigo AU: which is better for international travel?
Both currently offer zero forex and neither normally rewards foreign-currency transactions. Scapia is stronger if you value its domestic earn rates and unlimited spend-linked domestic Airport Privileges. ixigo AU becomes particularly interesting if you prefer ixigo travel discounts and its current domestic, railway and annual international lounge benefits.

Founder & Editor, CardRecommend
Founder & Editor of CardRecommend. Dedicated to researching credit card reward structures, fee waivers, airport lounge policies, and calculating real user value across Indian financial products.