Executive Summary
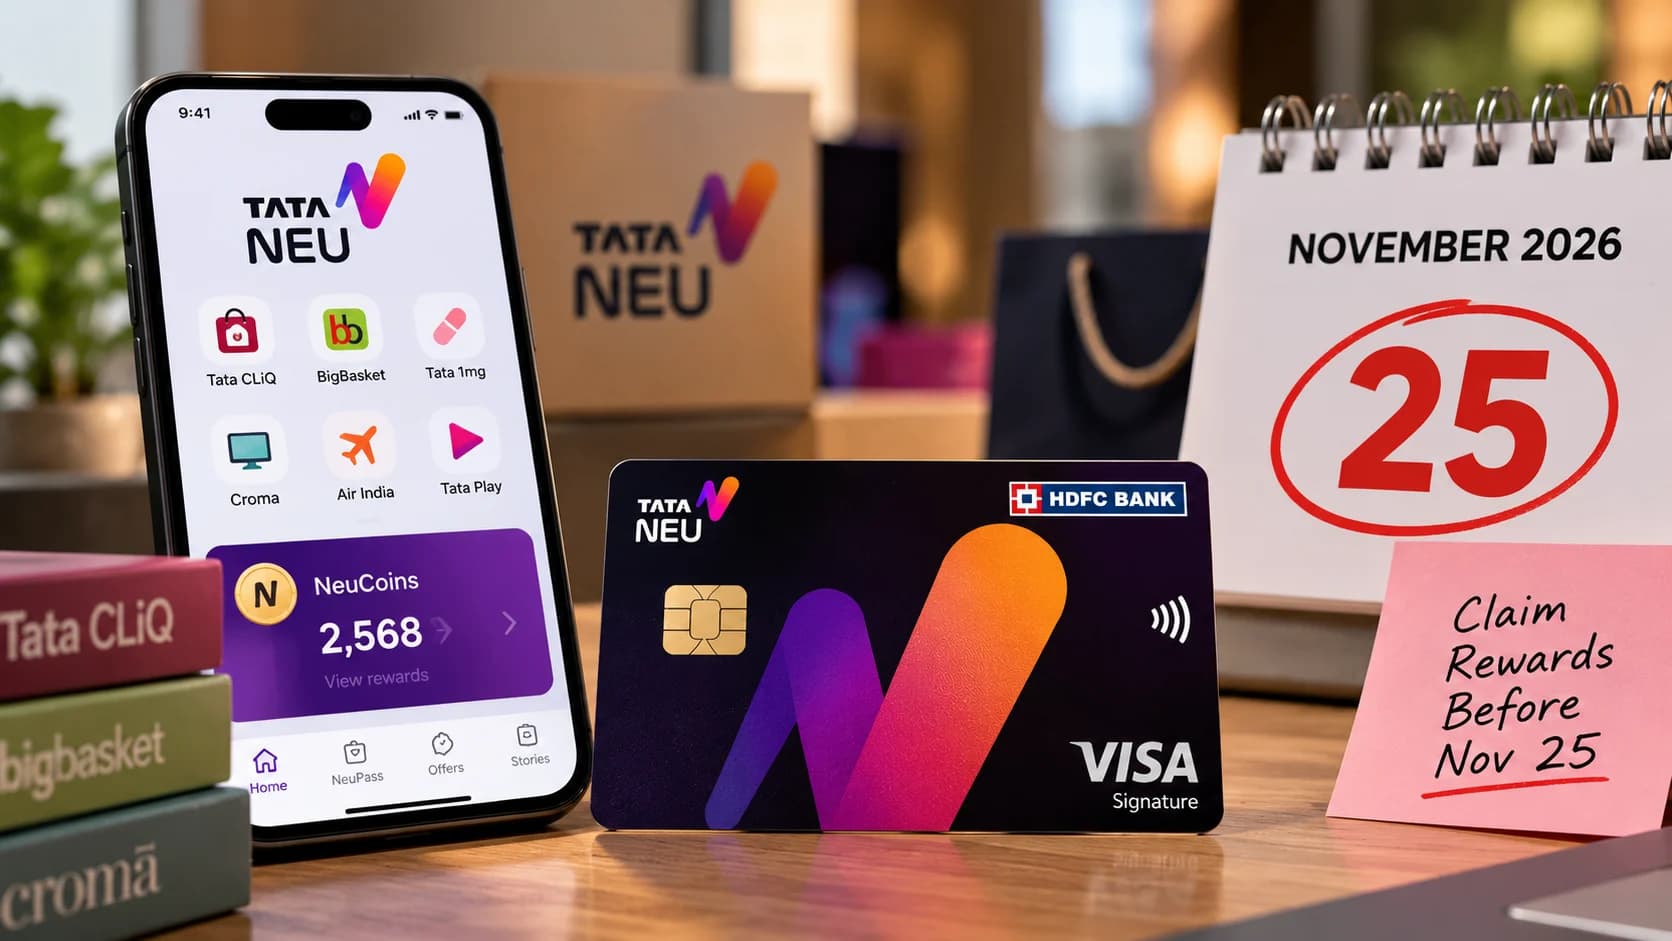
From 25 November 2026, NeuCoins earned on Tata Neu Infinity and Plus HDFC credit cards will no longer transfer automatically. Cardholders must manually claim them within 12 months or they expire. We explain the new rule, the hidden 2-year validity upside, and how HDFC compares with SBI.
Cards Compared
Tata Neu Infinity HDFC Bank Credit Card
Frequent shoppers across the Tata consumer ecosystem and digital spenders wanting maximum rewards on QR code merchant UPI payments.
Tata Neu Plus HDFC Bank Credit Card
Value-conscious consumers, BigBasket/1mg shoppers, and UPI spenders seeking an affordable entry point into the Tata Neu rewards ecosystem.
Tata Neu Infinity SBI Credit Card
Tata ecosystem loyalists who shop across Croma, BigBasket, Westside, Air India, and Tata CLiQ and want combined lounge access with a low 1.99% forex markup.
Tata Neu Plus SBI Credit Card
Value-seeking consumers who shop regularly on BigBasket, Croma, 1mg, Westside, and Tata CLiQ and want an affordable ₹499 card with lounge access and RuPay UPI support.
In This Guide
Tata Neu HDFC Bank Credit Card holders are about to get an extra monthly task.
From 25 November 2026, NeuCoins earned through the Tata Neu Infinity HDFC Bank Credit Card and Tata Neu Plus HDFC Bank Credit Card will no longer be automatically transferred to the cardholder's Tata Neu Membership account.
Instead, cardholders will have to open the Tata Neu app and manually claim them.
That sounds like a small operational change.
It is not.
Under HDFC Bank's new rules, NeuCoins that remain unclaimed for 12 months from the relevant credit-card statement date will expire.
So from November 25, it becomes possible to earn NeuCoins through legitimate card spending and then lose them simply because you forgot to press the claim button.
There is one unusual upside: after NeuCoins are successfully claimed and moved into the Tata Neu Membership account, they receive another 12-month validity period under the applicable Tata Neu Rewards rules.
That means disciplined users may actually be able to extend the practical life of their rewards.
But everyone else gets an additional expiry risk.
Terms verified: 24 October 2026
The Short Answer
From 25 November 2026:
- Tata Neu Infinity and Tata Neu Plus HDFC card rewards will no longer automatically move to Tata Neu.
- The primary cardholder must claim them through the Tata Neu app.
- Claimable NeuCoins become available within 7 working days of the card statement date.
- Each claim must currently be at least 100 NeuCoins.
- Up to 3 successful claims can be made per day.
- Unclaimed NeuCoins expire 12 months after the relevant statement date.
- After a successful claim, HDFC says it may take up to another 7 working days for the NeuCoins to reach Tata Neu.
- Once credited to the Tata Neu Membership account, claimed NeuCoins receive another 12-month validity period under the applicable reward terms.
This change affects credit-card-earned NeuCoins.
Promotional NeuCoins and welcome benefits continue to follow the specific expiry rules communicated for those offers.
What Changes on November 25?
The current process is simple.
You spend on the Tata Neu HDFC card.
NeuCoins are calculated.
After statement generation, eligible credit-card NeuCoins are periodically transferred to the Tata Neu Membership account.
From 25 November, the process becomes:
Earn → Statement → Wait for claimable balance → Open Tata Neu app → Claim → Wait for transfer → Redeem
HDFC says the claim process will be:
- Log in to Tata Neu using the primary cardholder's bank-registered mobile number.
- Open the NeuCard section.
- Select Claim NeuCoins.
- Complete the steps shown in the app.
The closing NeuCoins balance from the latest statement should become available for claiming within 7 working days from the statement date.
The Biggest Risk: Unclaimed NeuCoins Can Now Expire
This is the part existing cardholders should care about most.
HDFC says NeuCoins earned in a credit-card statement can be claimed for up to:
12 months from that statement date.
After that:
unclaimed NeuCoins expire.
HDFC's own example uses a statement generated on 15 December 2026.
Those NeuCoins should become claimable by around 22 December.
The cardholder then has until 14 December 2027 to claim them.
Miss that deadline and the unclaimed balance expires.
Previously, normal credit-card-earned NeuCoins did not require this manual step before being transferred into Tata Neu.
The November rule therefore creates an entirely new failure point.
There Is Also a 100 NeuCoin Minimum Claim
Each claim must currently contain at least:
100 NeuCoins
HDFC also limits the primary cardholder to:
3 successful claim requests per day.
For a heavy Tata Neu user, the 100-NeuCoin minimum should not be difficult.
For someone who barely uses the card, it could matter more.
Suppose a cardholder earns only 60 NeuCoins and then stops using the card.
They cannot currently submit a 60-NeuCoin claim because it sits below the published minimum.
They would need additional eligible NeuCoins to push the claimable balance above the threshold before the relevant balance expires.
HDFC does say the minimum claim amount may be revised downward in the future, with the applicable minimum shown in the app.
But I would not assume that will happen.
Claimed NeuCoins Get Another 12 Months
This is the interesting part.
Once the cardholder successfully claims the NeuCoins and they are credited into the Tata Neu Membership account, HDFC says they will be valid for another:
12 months
under the Tata Neu Rewards Program.
That creates a very different reward strategy.
Imagine you earn 5,000 NeuCoins in December 2026.
You could claim them immediately and start the Tata Neu validity clock.
Or, in theory, you could leave them in the HDFC card account for much of the permitted claim period and claim later.
Once credited into Tata Neu, the second validity period starts.
So someone managing the dates carefully could potentially keep the economic value alive for close to two years from earning.
That is the one real positive hidden in the new structure.
But it requires more effort and introduces the possibility of forgetting completely.
For most cardholders, automatic transfer was simpler.
This Is Different From the Existing NeuCoin Expiry Rule
Tata Neu HDFC rewards were already subject to expiry.
Since 1 August 2025, normal NeuCoins transferred into the Tata Neu account have generally carried a 12-month validity period.
So the November 2026 change does not introduce reward expiry from scratch.
It introduces something different:
Before November 25
Earn NeuCoins → automatic transfer to Tata Neu → 12-month Tata Neu validity
From November 25
Earn NeuCoins → remain claimable in HDFC card account → must claim within 12 months → transfer to Tata Neu → another 12-month Tata Neu validity
The first 12-month window is therefore a claim deadline.
The second is the redemption validity period after transfer.
That distinction matters.
What Happens to NeuCoins Earned Before November 25?
HDFC has addressed this directly.
NeuCoins earned on credit-card statements generated before 25 November 2026 will continue under the existing process.
They should be automatically transferred to the Tata Neu Membership account within 7 working days of statement generation.
They will then follow the existing 12-month post-credit validity treatment.
So this is not a retroactive manual-claim rule for every historical NeuCoin balance.
The new claim mechanism applies from the effective date.
Your Statement Will Warn You Before Claimable NeuCoins Expire
HDFC says monthly credit-card statements will identify NeuCoins that are approaching their claim expiry.
The statement can show balances scheduled to expire within the next:
30 days
or:
60 days
That is useful.
But I still would not rely on statement warnings alone.
If Tata Neu Infinity or Plus is a meaningful card in your wallet, the safest approach from November will be to make NeuCoin claiming part of your normal monthly card routine.
Billing-Cycle Changes Can Affect the Deadline
There is a less obvious rule hidden in HDFC's notice.
The claim deadline is linked to the card's statement cycle.
HDFC gives an example where NeuCoins originally earned on a statement dated 15 December 2026 could normally be claimed until 14 December 2027.
But if the customer's statement date is later changed to the 10th of the month, HDFC says that balance may instead need to be claimed by 9 December 2027.
So changing your billing cycle can move the expiry deadline.
That is another reason to avoid waiting until the final few days.
Closed or Blocked Cards Create Another Risk
HDFC says NeuCoin claims will not be allowed when the Tata Neu HDFC credit card is:
- closed, or
- blocked.
That creates an important operational rule.
Do not close the card while you still have a meaningful unclaimed NeuCoin balance.
Claim the eligible balance first.
If a card is temporarily blocked and subsequently unblocked through the bank, HDFC says it can take up to three working days before NeuCoin claiming becomes available again.
What If Your Card Is Lost, Reissued or Changed?
There is some protection here.
If the card is lost or reissued, HDFC says an existing unclaimed NeuCoin balance will be transferred to the new card within around 7 working days.
The balance should then become available for claiming through the Tata Neu app after the applicable statement process.
A similar mechanism applies when moving between Tata Neu HDFC variants.
That reduces the risk of instantly losing rewards simply because the physical card changes.
The Reward Rates Are Not Being Cut in This Update
This is important.
The November announcement changes how credit-card-earned NeuCoins reach Tata Neu.
It does not announce a new reduction in the normal Infinity or Plus earning rates.
Tata Neu Infinity
Current HDFC terms continue to show:
- 5% back as NeuCoins on eligible non-EMI Tata partner spending
- 1.5% on eligible non-Tata spending
- up to 1.5% on eligible RuPay UPI spending
- 0.50% through other eligible UPI IDs
- additional 1% when using the Tata Neu UPI ID
- UPI NeuCoins capped at 500 per calendar month
- additional NeuPass rewards on selected Tata Neu categories
Tata Neu Plus
Current terms continue to show:
- 2% on eligible Tata partner spending
- 1% on eligible non-Tata spending
- up to 1% on eligible RuPay UPI spending
- 0.25% through other eligible UPI IDs
- additional 0.75% through the Tata Neu UPI ID
- UPI NeuCoins capped at 500 per calendar month
- additional NeuPass rewards on selected Tata Neu categories
So this is a reward-access devaluation, not an earning-rate devaluation.
You can still earn the same published rates.
You simply have more work to do before the rewards become usable.
Tata Neu Infinity Is Still the Better HDFC Variant
For someone choosing between Infinity and Plus, this November change does not alter the basic hierarchy.
Tata Neu Infinity remains the stronger card if you can justify its fee and use the Tata ecosystem heavily.
Its standard pricing is:
₹1,499 + applicable taxes
with renewal fee waiver after:
₹3 lakh annual spending.
Tata Neu Plus costs:
₹499 + applicable taxes
with renewal waiver after:
₹1 lakh annual spending.
Infinity earns more on both Tata spending and ordinary eligible card spending.
The manual-claim friction affects both.
So it does not suddenly make Plus the better version.
Does This Make Tata Neu Infinity No Longer Worth It?
No.
But it makes the card less convenient.
Tata Neu Infinity still has an unusually strong combination for someone already spending across brands such as:
- BigBasket
- Croma
- Tata 1mg
- IHCL
- Westside
- Tata CLiQ
- Titan
- Tanishq
- Air India / Air India Express where eligible under current terms
Its 5% core Tata-brand earning, additional NeuPass opportunities and 1.5% eligible general-spend rate remain competitive.
For RuPay users, up to 1.5% on eligible UPI spending is also useful.
The problem is no longer earning.
The problem is reward management.
A good card has become slightly more annoying to own.
The New System Can Punish Casual Cardholders More Than Power Users
Someone using Tata Neu Infinity every month will probably see the claim option frequently and build a habit around it.
A casual user is more vulnerable.
Imagine using the card heavily during a sale, earning several thousand NeuCoins, then putting it in a drawer.
Under the new system, those rewards may sit in the HDFC card account rather than reaching Tata Neu automatically.
If you forget about them for a year, they can disappear.
That is exactly the kind of friction that benefits an issuer when customers are inattentive.
CardRecommend should therefore treat manual claim required as a meaningful rewards-program condition on both HDFC Tata Neu card pages.
Tata Neu SBI Now Has an Important Convenience Advantage
There is another consequence.
SBI Card now issues its own Tata Neu Infinity SBI and Tata Neu Plus SBI cards.
Under SBI Card's current published terms, earned NeuCoins continue to be automatically transferred to the cardholder's NeuPass account around the statement cycle.
That means HDFC's new manual-claim requirement gives the SBI versions a genuine convenience advantage.
Tata Neu Infinity SBI
The current SBI proposition includes:
- 5% NeuCoins on eligible Tata Neu / Tata partner spending
- additional rewards on selected Tata Neu categories
- 1.5% on eligible other spending, including UPI on the RuPay variant
- automatic NeuCoin transfer
- ₹1,499 + taxes annual fee
- ₹3 lakh annual-spend fee waiver
That looks remarkably similar to HDFC Infinity at the headline reward level.
But after November 25:
HDFC Infinity → manual claim
SBI Infinity → automatic transfer under current published SBI terms
That does not automatically make SBI the better card overall.
The cards differ in areas such as lounge access, forex markup, issuer offers and other servicing benefits.
But if you are applying primarily for Tata Neu rewards, the reward-crediting process is now a legitimate differentiator.
Should Existing HDFC Infinity Holders Switch to SBI?
I would not switch solely because of the claim button.
Moving issuers can mean:
- another credit enquiry
- a new credit line
- potentially different limits
- different lounge rules
- different bank offers
- a second annual fee
If your HDFC Infinity card is already lifetime free, the argument for keeping it becomes even stronger.
You simply need to remember to claim the rewards.
But if you are a new applicant deciding between the HDFC and SBI Tata Neu variants, manual versus automatic reward transfer should now be part of the comparison.
It was not before.
Reddit Reaction Is Predictably Negative
The reaction from Indian credit-card communities has focused less on the 12-month window and more on the principle of the change.
Users are asking why they should need to manually claim rewards that were already earned through eligible card transactions.
Others are worried they will simply forget.
That criticism is reasonable.
There is also a smaller group pointing out the strategic upside: if you wait to claim, the later 12-month Tata Neu validity can effectively extend how long you keep the rewards alive.
That interpretation is also reasonable.
The change is therefore not mathematically disastrous.
It is simply less customer-friendly.
Reddit should not be used to establish the terms, but it accurately captures the practical problem:
another thing to remember.
The Best Strategy From November 25
For most users, I would keep this simple.
After each statement:
- Wait until your claimable NeuCoins become available.
- Open Tata Neu.
- Go to NeuCard.
- Check the claimable balance.
- Claim it.
Do not optimise for a theoretical extra year unless you actually need to preserve the rewards for a future large Tata purchase.
The value of avoiding expiry is greater than the value of squeezing every possible month out of the validity window.
For someone intentionally accumulating NeuCoins for a large Croma, IHCL or Tanishq purchase, delaying the claim may make sense.
For everyone else:
claim monthly and forget about it.
Compare Tata Neu Infinity HDFC vs SBI
Compare reward crediting terms, lounge access, forex markup, and fee waivers head-to-head between HDFC and SBI Tata Neu variants.
Calculate Your Tata Neu Rewards on RuPay UPI
Estimate your monthly NeuCoins yield across Tata brand spends, UPI merchant payments, and standard retail transactions in CardRecommend's directory.
CardRecommend Verdict
Tata Neu Infinity remains worth holding after the November 25 NeuCoins change, but HDFC has made a strong rewards card unnecessarily harder to use.
The earning rates have not been cut in this update.
Infinity still offers 5% on eligible Tata-brand spending, 1.5% on eligible non-Tata spending and up to 1.5% on eligible UPI spending under the current structure.
Tata Neu Plus retains its lower 2% / 1% / up-to-1% reward structure.
So I would not cancel either card purely because manual claiming is being introduced.
But CardRecommend should treat this as a real devaluation in convenience.
From November 25, cardholders can lose rewards they have already earned simply by failing to claim them within the required window.
The 100-NeuCoin minimum also adds unnecessary friction for light users.
There is one compensating benefit: claimed NeuCoins receive another 12-month validity period after entering Tata Neu, so a disciplined user can effectively extend reward life by delaying the claim.
But that is an optimisation opportunity, not a justification for adding complexity.
For an existing HDFC Infinity holder who uses the Tata ecosystem heavily:
keep the card and make claiming NeuCoins part of your monthly statement routine.
For an existing lifetime-free Infinity holder:
I would definitely not close it over this change alone.
For a new applicant deciding between HDFC and SBI Tata Neu cards:
the SBI version now has a genuine convenience advantage because its current terms continue to provide automatic NeuCoin transfer.
Tata Neu Infinity is still a strong card.
It is simply no longer as effortless as it was.
Cards Discussed in This Article
Frequently Asked Questions
When does the new Tata Neu HDFC NeuCoins claim rule start?
The new manual claim process takes effect on 25 November 2026.
Which cards are affected?
The rule applies to Tata Neu HDFC Bank Credit Cards, including:
- Tata Neu Infinity HDFC Bank Credit Card
- Tata Neu Plus HDFC Bank Credit Card
Will NeuCoins still be credited automatically?
Not for affected credit-card-earned NeuCoins from the new process.
The primary cardholder will need to claim them through the Tata Neu app.
How do I claim Tata Neu HDFC NeuCoins?
Log in to Tata Neu using the bank-registered mobile number, open the NeuCard section and select Claim NeuCoins.
When do NeuCoins become available to claim?
HDFC says the closing NeuCoin balance from the latest credit-card statement should become available within 7 working days of the statement date.
How long do I have to claim them?
NeuCoins must be claimed within 12 months of the statement date in which they were earned.
Unclaimed NeuCoins expire after that period.
What is the minimum claim amount?
The current minimum is:
100 NeuCoins per claim
HDFC allows up to three successful claims per day.
How long does it take for claimed NeuCoins to appear in Tata Neu?
HDFC says it can take up to 7 working days after a successful claim.
How long are NeuCoins valid after I claim them?
Once claimed and credited to the Tata Neu Membership account, they receive another 12-month validity period under the applicable Tata Neu Rewards Program terms.
What happens to NeuCoins earned before November 25?
NeuCoins earned in statements before the effective date continue under the existing automatic-transfer process and applicable post-credit validity.
Does the new rule reduce Tata Neu Infinity's reward rate?
No reward-rate cut has been announced as part of this change.
The change concerns how earned NeuCoins are transferred and claimed.
Does this apply to Tata Neu SBI Cards?
Current SBI Card terms still state that NeuCoins are automatically credited/transferred to the cardholder's NeuPass account around the monthly statement cycle.
The HDFC manual-claim change should therefore not be automatically applied to Tata Neu SBI cards.

Founder & Editor, CardRecommend
Founder & Editor of CardRecommend. Dedicated to researching credit card reward structures, fee waivers, airport lounge policies, and calculating real user value across Indian financial products.