Executive Summary
A lifetime-free RuPay card against a ₹2,000 FD sounds ordinary. 10% rewards on UPI doesn't. We break down the 5% card + 5% novio UPI Coin math, 500-Coin daily cap, Go vs Prime, fuel exclusions, ₹599 early closure fee, and why 10 novio Coins is not ₹10 cashback in 2026.
Subject Cards
DCB novio Go Credit Card
Credit building, new-to-credit customers, and daily UPI payments via novio app with zero annual fees.
DCB novio Prime Credit Card
Secured cardholders seeking complimentary domestic airport lounge access alongside daily UPI rewards.
In This Guide
A lifetime-free RuPay credit card against a ₹2,000 fixed deposit sounds fairly ordinary.
10% rewards on UPI doesn't.
That's the number novio is using to sell the DCB novio Credit Card: make an eligible merchant payment using the DCB novio RuPay card through novio UPI and the current structure promises 5% novio Coins from the card + another 5% from novio UPI = 10% Coins.
But this is the important distinction:
10 novio Coins earned on ₹100 of spending is not ₹10 cashback.
novio's own rewards terms say its Coins have no inherent monetary value, cannot ordinarily be converted to cash and must be redeemed against whatever vouchers, discounts or other options novio makes available inside the app. Even gift vouchers cannot be purchased entirely using Coins; some additional payment is required.
That changes the entire economics of this card.
The DCB novio Credit Card is still an interesting product — particularly for someone with no credit history — but we'd judge it primarily as an accessible FD-backed credit-building card with an unusual rewards ecosystem, not as a verified 10% cashback machine.
DCB novio Credit Card: The Important Numbers
| Feature | Current terms |
|---|---|
| Issuer | DCB Bank |
| Network | RuPay |
| Card type | Secured / FD-backed |
| Joining fee | ₹0 |
| Annual fee | ₹0 |
| Minimum FD | ₹2,000 for Go according to current DCB/novio disclosures |
| Credit limit | 90% of linked FD |
| Physical card | Free once cumulative FD reaches ₹10,000 |
| Prime minimum FD | ₹25,000 |
| Finance charge | 3% per month / 36% annualised |
| Forex markup | 2.5% |
| Interest-free period | 15–45 days |
| Early card closure | ₹599 if closed within first year |
| UPI reward headline | Up to 10% novio Coins through novio UPI |
| P2M Coin cap | 500 Coins per day |
| Annual fee | Lifetime free under current KFS |
DCB Bank's April 2026 KFS confirms that both the RuPay Platinum and RuPay Select variants have no joining or annual fee. It also confirms that the credit limit is 90% of the lien-marked FD and that a free physical card is available once cumulative FD reaches ₹10,000.
There is one qualification to “lifetime free”: closing the DCB novio card within the first year currently costs ₹599. So the membership is lifetime free, but exiting early isn't necessarily free.
Explore DCB novio Credit Card Options
Choose between the accessible ₹2,000 FD Go variant (RuPay Platinum) or the ₹25,000 FD Prime variant (RuPay Select with quarterly domestic lounge access).
What Exactly Is DCB novio?
This is not an unsecured credit card where DCB Bank evaluates your salary and gives you a large credit limit.
You first create a DCB Bank fixed deposit. The bank places a lien on that deposit and issues a secured RuPay credit card against it.
Your credit limit is currently 90% of the linked FD.
That produces:
| Linked FD | Approx. credit limit |
|---|---|
| ₹2,000 | ₹1,800 |
| ₹5,000 | ₹4,500 |
| ₹10,000 | ₹9,000 |
| ₹25,000 | ₹22,500 |
| ₹50,000 | ₹45,000 |
The ₹2,000 entry point is real according to DCB's own 2026 investor disclosure and the current novio comparison table. novio also markets the product as requiring no income proof and no previous credit history.
But ₹2,000 should not be confused with a practically useful credit limit for heavy UPI spending.
A ₹1,800 limit is enough to start using a credit card and establish repayment history. It isn't enough for someone intending to route ₹10,000–₹20,000 of monthly spending through the card.
For that, you'll need a larger FD.
DCB novio Go vs Prime
novio currently presents two DCB variants: Go and Prime. Bank documents describe the corresponding legal card variants as RuPay Platinum and RuPay Select.
| Feature | DCB novio Go | DCB novio Prime |
|---|---|---|
| Corresponding network tier | RuPay Platinum | RuPay Select |
| Minimum FD | ₹2,000 | ₹25,000 |
| Credit limit | 90% of FD | 90% of FD |
| Joining/annual fee | Nil | Nil |
| Virtual card | Yes | Yes |
| Physical card | From cumulative ₹10,000 FD | Yes at ₹25,000 FD |
| Domestic lounge access | None | 1 per quarter / 4 per year |
| International lounge | None | None |
| Core novio rewards/offers | Yes | Yes |
The lounge distinction is confirmed by DCB's current MITC: Platinum gets no complimentary lounge access, while Select gets one domestic airport lounge visit per quarter, capped at four per year. Unused visits lapse and a ₹2 validation charge applies.
Is Prime worth locking ₹25,000?
Not purely for rewards.
The ₹25,000 FD gives you roughly ₹22,500 of credit limit and unlocks four domestic lounge visits a year. If you genuinely use those lounges, Prime becomes more sensible.
If all you want is UPI rewards or credit building, Go offers the same fundamental card-and-UPI proposition without requiring ₹25,000.
The FD itself continues earning interest — novio currently advertises up to 7% on the linked deposit — so the ₹25,000 isn't sitting completely idle. But it remains lien-marked against the card rather than freely available cash.
How Does the Advertised 10% on UPI Actually Work?
This part is unusually straightforward.
For an eligible merchant P2M transaction made through novio UPI using a novio RuPay Credit Card, novio currently says:
5% novio Card Earn
+
5% novio UPI Earn
=
10% novio Coins
Suppose you scan a restaurant's QR and pay ₹1,000.
DCB novio + novio UPI
Eligible spend: ₹1,000
Card earn: 50 Coins
novio UPI earn: 50 Coins
Total: 100 Coins
That's the full advertised 10% Coin earning.
DCB novio through Google Pay or PhonePe
You can link the DCB RuPay card to supported third-party UPI apps. DCB itself has said the card can be used through platforms including novio, PhonePe and Google Pay.
But the extra novio UPI 5% belongs specifically to transactions through novio UPI.
So don't expect the full 10% structure simply because you've linked DCB novio to Google Pay or PhonePe.
The card-side reward may still apply subject to the applicable rewards terms, but the separate novio-UPI component requires novio UPI.
Normal bank account through novio UPI
Interestingly, novio currently gives 5% Coins on eligible P2M transactions even when another payment instrument is used.
Its terms also say eligible P2P payments from other instruments can earn 5% Coins.
That doesn't mean you can use the DCB RuPay credit card to transfer money to friends.
NPCI prohibits P2P, P2PM, card-to-card payments and cash withdrawals through the RuPay-credit-card-on-UPI facility. RuPay credit cards on UPI are fundamentally for eligible merchant transactions.
The 500-Coin Daily Cap Changes the Maths
Eligible merchant UPI rewards are capped at 500 novio Coins per day.
At a 10% Coin earning rate:
₹5,000 eligible spend × 10% = 500 Coins
So spending more than ₹5,000 of otherwise eligible DCB-novio-through-novio-UPI transactions in a single day doesn't increase that day's Coin earning beyond 500.
That makes spending pattern important.
| Monthly eligible UPI spending | If sufficiently spread across days | If all spent in one day |
|---|---|---|
| ₹5,000 | 500 Coins | 500 Coins |
| ₹10,000 | 1,000 Coins | 500 Coins |
| ₹20,000 | 2,000 Coins | 500 Coins |
| ₹40,000 | 4,000 Coins | 500 Coins |
For ₹40,000 of eligible spend, you'd need to spread transactions across at least eight days at no more than ₹5,000 of rewardable spending per day to theoretically earn the full 4,000 Coins.
That's before exclusions.
But What Is One novio Coin Actually Worth?
This is where the headline falls apart.
There is currently no permanent, universal official conversion saying 1 novio Coin = ₹1, ₹0.50, ₹0.20 or any other fixed amount.
The rewards terms explicitly say:
- Coins have no inherent monetary value;
- they cannot normally be converted to cash;
- they are non-transferable;
- redemption options can change;
- brands and discounts can change;
- Coins may be used for selected gift cards or services;
- gift cards cannot be purchased using Coins alone;
- additional payment is required.
novio currently markets voucher discounts of up to roughly 18–20%, but that is a discount unlocked through the redemption ecosystem. It is not evidence that every Coin is worth a fixed number of paise.
So this statement would be wrong:
Spend ₹100 → earn 10 Coins → receive ₹10 value.
Current official terms simply don't support it.
A revealing September promotion
There is one useful piece of historical evidence.
During a targeted September 2026 Coins-to-cash promotion, novio temporarily valued eligible Coins at:
5 Coins = ₹1
with cashback capped at ₹100.
That would imply:
10 Coins = ₹2
or a 2% cash-equivalent return on a ₹100 transaction earning 10 Coins.
But this was a limited promotional conversion for selected customers and ended in September. It is not the normal redemption rate and should not be used as the permanent value of novio Coins.
Still, it demonstrates exactly why “10% Coins” and “10% cashback” are not interchangeable.
So How Much Does a ₹10,000 UPI User Really Earn?
In Coins, we can calculate it.
In rupees, we can't honestly give a universal answer.
Assuming every transaction qualifies and the user spreads spending sufficiently to avoid the daily cap:
₹5,000/month
500 Coins
₹10,000/month
1,000 Coins
₹20,000/month
2,000 Coins
₹40,000/month
4,000 Coins
But CardRecommend would not convert those into ₹500, ₹1,000, ₹2,000 and ₹4,000 of reward value.
That would amount to inventing a ₹1-per-Coin valuation that novio itself does not provide.
Your actual value depends on what redemption options happen to be available, how many Coins they consume, how much cash/UPI payment is still required, and whether you actually want the voucher.
That is the biggest weakness in the reward programme.
A Flat 1.5% Cashback Card Can Beat “10% Coins”
Consider ₹10,000 of eligible UPI spending.
DCB novio through novio UPI:
1,000 novio Coins
But there is no guaranteed permanent rupee value for those Coins.
Kiwi currently advertises 1.5% flat cashback on eligible Scan & Pay UPI transactions, with the cashback going directly to the user's bank account.
₹10,000 × 1.5% = ₹150 real cashback.
At ₹20,000:
₹300 real cashback.
Axis super.money's current SuperCard Pro goes further, advertising 3% cashback on superUPI transactions with no cap, while remaining lifetime free.
That means the comparison isn't:
10% vs 1.5%
or
10% vs 3%.
It's:
10 Coins per ₹100 with variable redemption value
versus
₹1.50 or ₹3 of actual cashback per ₹100 where the relevant cashback terms are satisfied.
Those are fundamentally different products.
For someone who values predictability, we prefer actual cashback.
Not Every UPI Transaction Earns Coins
novio's current UPI rewards terms exclude several transaction types, including:
- utilities;
- government payments;
- insurance;
- educational institutions;
- gambling;
- railways;
- quasi-cash;
- cash withdrawals;
- UPI Lite;
- failed, pending or reversed transactions.
Transactions where the calculated Coin amount rounds down to zero also receive nothing.
DCB Bank's own MITC additionally lists rent, wallet loading, online gaming, gambling, fuel and cash withdrawal as excluded from its reward calculation.
And that creates an important problem.
Is Fuel Really 10%?
novio's current marketing page says:
10% novio Coins on fuel purchases.
DCB Bank's April 2026 MITC says:
fuel transactions are excluded from reward calculation.
Those two statements don't reconcile cleanly.
The card separately provides a 1% fuel surcharge waiver capped at ₹100 per statement cycle on eligible fuel spending up to ₹5,000, which is confirmed in DCB's KFS.
But until DCB updates its legal reward documentation or novio publishes DCB-specific terms clearly overriding the older exclusion, CardRecommend would not advertise 10% fuel Coins as a verified DCB novio benefit.
The issuer's MITC carries more weight than a marketing banner.
What About the ₹23,000 Annual Savings Claim?
This claim becomes much easier to understand once you break it down.
novio currently advertises combinations including:
BookMyShow: BOGO worth up to ₹250 once per month Maximum annual headline value: ₹3,000
Amazon: up to ₹1,000 discount per month on ₹20,000 eligible purchases Maximum annual headline value: ₹12,000
Zepto: ₹50 off ₹499, up to three times monthly Maximum annual headline value: ₹1,800
Swiggy: up to ₹100 off monthly Maximum annual headline value: ₹1,200
These four together:
₹3,000 + ₹12,000 + ₹1,800 + ₹1,200 = ₹18,000
Add the advertised welcome package:
up to ₹5,000
and you reach:
₹23,000.
So ₹23,000 isn't fabricated.
But achieving it means using almost every promoted benefit at or near its maximum frequency, including spending enough on Amazon every month to claim the maximum monthly discount.
That's very different from a normal cardholder automatically receiving ₹23,000 of annual value.
We wouldn't add ₹23,000 to our reward valuation.
The ₹5,000 Welcome Benefit Also Needs Context
To qualify for the current welcome offer, novio requires you to:
activate the card;
make at least one transaction;
and spend ₹2,500 within 30 days of card issuance.
The resulting benefit is a package of vouchers/discounts rather than ₹5,000 deposited into your account.
The exact brands may change, the benefits cannot be converted to cash, and voucher codes expire 90 days after issuance.
Again, “worth ₹5,000” is not the same as ₹5,000 cashback.
There Is a Real Cashback Promotion Right Now
As of 26 October 2026, DCB novio is running a separate temporary cashback campaign covering eligible spends from 1 October to 30 November 2026.
For DCB novio cardholders who explicitly opt in:
| Eligible campaign spend | Promotional cashback |
|---|---|
| ₹10,000 | ₹200 |
| ₹25,000 | ₹500 |
| ₹50,000 | ₹1,500 |
| ₹1,00,000 | ₹5,000 |
This is actual promotional cashback, not novio Coins. The campaign also has its own excluded MCCs and eligibility conditions and ends on 30 November 2026.
We would mention it in an article published today, but not bake it into the permanent card rating.
Is DCB novio Actually Lifetime Free?
Yes on membership charges.
DCB's latest KFS lists:
Joining fee: Nil
Annual fee: Nil
for both Platinum and Select variants.
Other costs matter:
| Charge | Current DCB terms |
|---|---|
| Finance charge | 3% monthly / 36% annualised |
| Forex markup | 2.5% |
| Late fee, outstanding ≤ ₹100 | Nil |
| Late fee, ₹101–₹1,000 | ₹100 |
| Late fee above ₹1,000 | ₹500 |
| Domestic ATM withdrawal | 2.5% or ₹299, whichever is higher |
| Early closure within one year | ₹599 |
| Card replacement/reissue | ₹250 |
| GST | Applicable on relevant charges |
The interest-free period is currently 15–45 days, depending on when you purchase relative to the billing date.
You receive that grace period only when the previous month's balance has been paid in full and you haven't used the ATM cash facility.
What Happens to the FD?
The FD is collateral for the card.
DCB's MITC says users can increase or decrease the credit limit by adding or delinking linked FDs through the app, subject to the bank's rules.
But the bank has a lien over those deposits while they secure your card obligations.
If payments remain unpaid, DCB has the right to use or ultimately liquidate the linked collateral to recover card dues. The MITC says the bank can liquidate the collateral if minimum dues remain unpaid up to 85 days past due.
So don't think of the FD as completely independent money while the card remains secured against it.
Is the ₹2,000 Version Actually Useful?
As a rewards card, not really.
As an entry-level credit-building tool, yes.
₹2,000 FD gives roughly:
₹1,800 credit limit.
That is enough for a few small UPI transactions and regular repayment behaviour.
It isn't enough to exploit ₹10,000–₹20,000 monthly UPI spending.
For ₹10,000 of available credit alone, you'd need a linked FD of more than roughly ₹11,100.
At ₹25,000 FD, Prime gives approximately ₹22,500 credit limit.
That makes Prime substantially more usable for everyday spending, although repeatedly using most of a ₹22,500 limit every statement cycle would also produce high credit utilisation. How much that affects an individual's credit score varies, so we wouldn't promise any specific score improvement.
Does DCB novio Require Income Proof or Existing CIBIL History?
novio markets its FD-backed cards specifically to new-to-credit users and says no income proof and no previous credit history are required. DCB also describes novio as a secured card aimed at new-to-credit consumers.
Approval remains subject to KYC and bank checks.
This is one of the card's strongest advantages.
Someone who cannot qualify for a normal unsecured RuPay cashback card may still have a realistic route into formal credit by pledging their own FD.
We would not promise a specific CIBIL score or tell someone that the card automatically produces a 750+ score. Responsible repayment can help build credit history; the final score is determined by the credit bureau using multiple factors.
Apply for DCB novio Go (₹2,000 Minimum FD)
Start building credit history against an FD starting at ₹2,000 with no income proof and no prior CIBIL score required.
DCB novio vs Better-Known UPI Alternatives
| Card / ecosystem | UPI reward headline | Actual reward | FD required | Annual fee | Redemption | Action |
|---|---|---|---|---|---|---|
| DCB novio | 10% Coins via novio UPI | novio Coins, no permanent ₹ value | Yes | ₹0 | Variable voucher/discount ecosystem | Compare → |
| 1.5% standard | Real cashback | No for standard cards | ₹0 | Bank-account cashback | ||
| 3% on superUPI | Cashback | No | ₹0 | Cashback | ||
| Up to 2% Paytm UPI | Reward points; Paytm says ₹1/point for Gold redemption | No | ₹0 | Paytm Gold/vouchers/bill payments |
This table explains why we don't think “10%” automatically makes DCB novio the winner.
If you're eligible for an unsecured cashback card, 3% actual cashback is much easier to value than 10% Coins with no fixed redemption value.
But those cards aren't necessarily substitutes for someone with no credit history who specifically needs an FD-backed approval route.
That's where DCB novio becomes more compelling.
Explore DCB novio Credit Card Options
Choose between the accessible ₹2,000 FD Go variant (RuPay Platinum) or the ₹25,000 FD Prime variant (RuPay Select with quarterly domestic lounge access).
Apply for DCB novio Go (₹2,000 Minimum FD)
Start building credit history against an FD starting at ₹2,000 with no income proof and no prior CIBIL score required.
Apply for DCB novio Prime (Lounge Perks)
Genuine ₹0 joining and annual fees, 90% credit limit against fixed deposit, domestic lounge access, and RuPay UPI support.
CardRecommend Verdict
DCB novio is not a 10% cashback credit card. We would not market it as one.
The current reward structure genuinely gives up to 10 novio Coins per ₹100 of eligible merchant UPI spending when the DCB novio card is used through novio UPI. That part is real.
But those 10 Coins don't have a guaranteed ₹10 value.
novio explicitly states that Coins have no inherent monetary value, cannot normally be cashed out and depend on a changing voucher/redemption catalogue. The 500-Coin daily cap, excluded categories and need to use novio UPI for the full 10% structure further narrow the proposition.
That makes it impossible to honestly say that someone spending ₹10,000 a month receives a guaranteed ₹1,000 return.
They receive up to 1,000 Coins under the ideal spending pattern. What those Coins are worth depends on how they're eventually redeemed.
For pure UPI rewards, we'd rather have 1.5%–3% transparent cashback from a strong standalone UPI credit card than chase a larger Coin number with an uncertain rupee value.
But DCB novio wins a different argument.
It is genuinely lifetime free on annual membership charges, requires no conventional income-based credit approval, can start against an FD as low as ₹2,000, gives 90% of the FD as credit limit and supports RuPay UPI. Prime also adds four domestic lounge visits a year.
So we see DCB novio primarily as a credit-building card with an interesting rewards layer — not primarily as India's most rewarding UPI card.
Who should get it?
Someone who is new to credit, can't easily obtain an unsecured card, wants to build credit history using an FD-backed card, uses UPI heavily and doesn't mind optimising novio's own app and voucher ecosystem.
Who should skip it?
Someone who already qualifies for good unsecured RuPay cards and simply wants predictable UPI cashback.
For that user, the Coin system adds unnecessary complexity.
Go or Prime?
Go makes more sense for someone testing the product or primarily building credit.
Prime becomes worthwhile if you genuinely want the higher ₹22,500+ credit limit generated from a ₹25,000 FD and will use the four annual domestic lounge visits.
We would not lock ₹25,000 solely to access the same novio Coin system.
The biggest catch
It's not the FD.
It's not even the daily cap.
It's the unit of reward itself.
“10% novio Coins” looks dramatically better than “1.5% cashback” on an advertisement.
Until novio gives those Coins a stable rupee redemption value, that comparison is misleading.
DCB novio may have one of the highest advertised reward numbers among UPI credit cards.
We don't yet have enough evidence to call it one of India's highest actual monetary returns.
Apply for DCB novio Prime (Lounge Perks)
Genuine ₹0 joining and annual fees, 90% credit limit against fixed deposit, domestic lounge access, and RuPay UPI support.
Recommended Alternatives
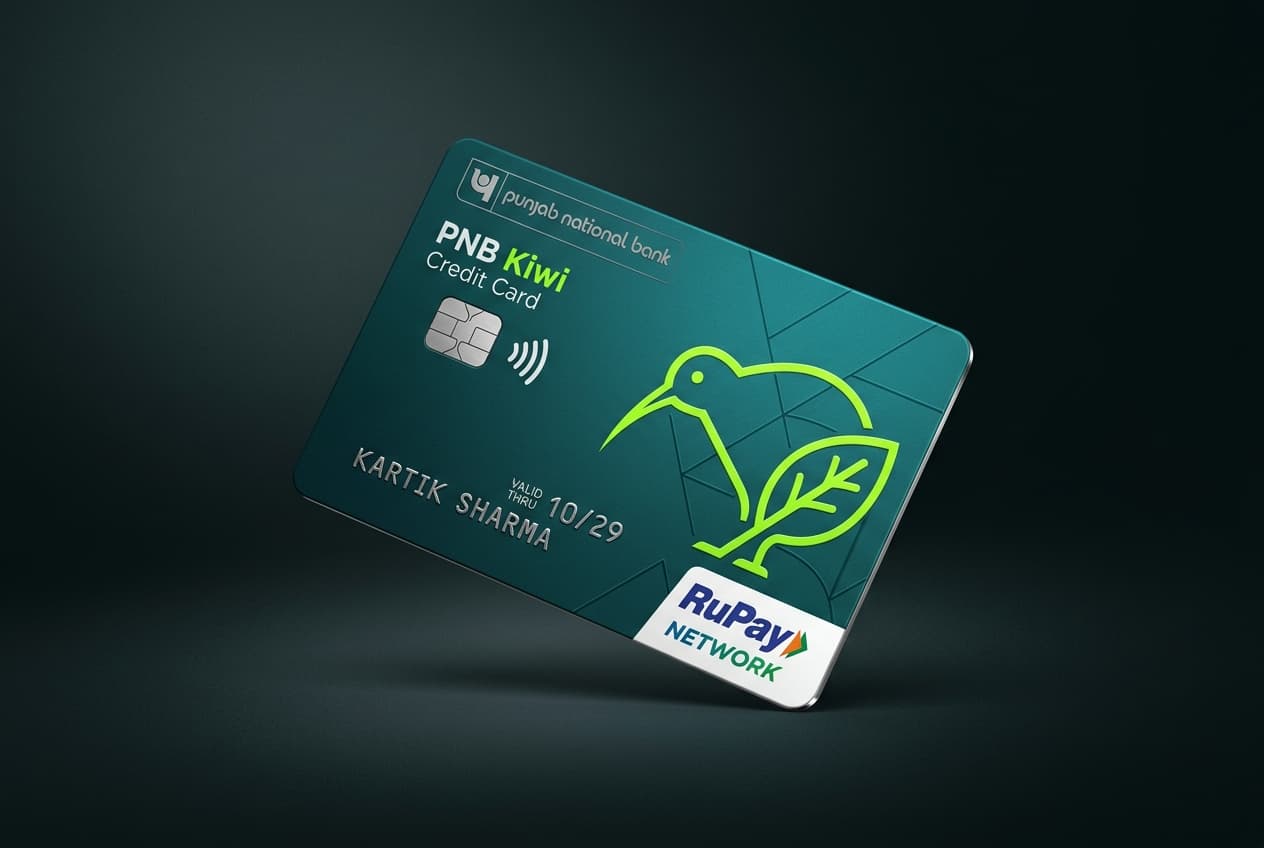
PNB Kiwi Credit Card
Daily digital spenders, mobile UPI QR payments, and consumers looking for a lifetime free RuPay credit card with direct cashback conversion.
Axis Bank SuperMoney RuPay Credit Card
UPI-first spenders who want a zero-fee credit card for everyday QR code payments at kirana stores, local shops, and online merchants with automatic cashback.
IDFC FIRST WOW! Credit Card
Credit builders, students, freelancers without income proof, and overseas travelers seeking a guaranteed-approval card with zero foreign exchange fees and high FD interest.
Cards Discussed in This Review
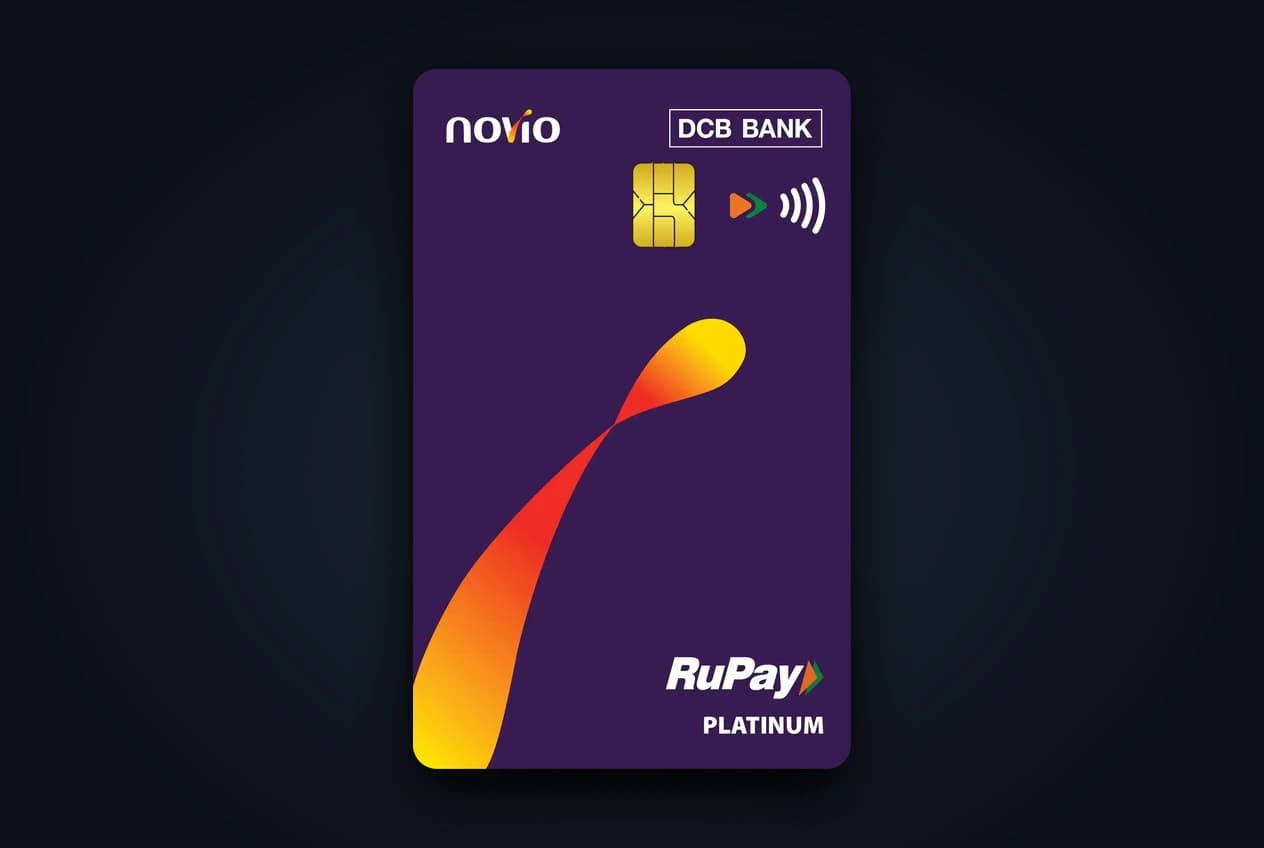
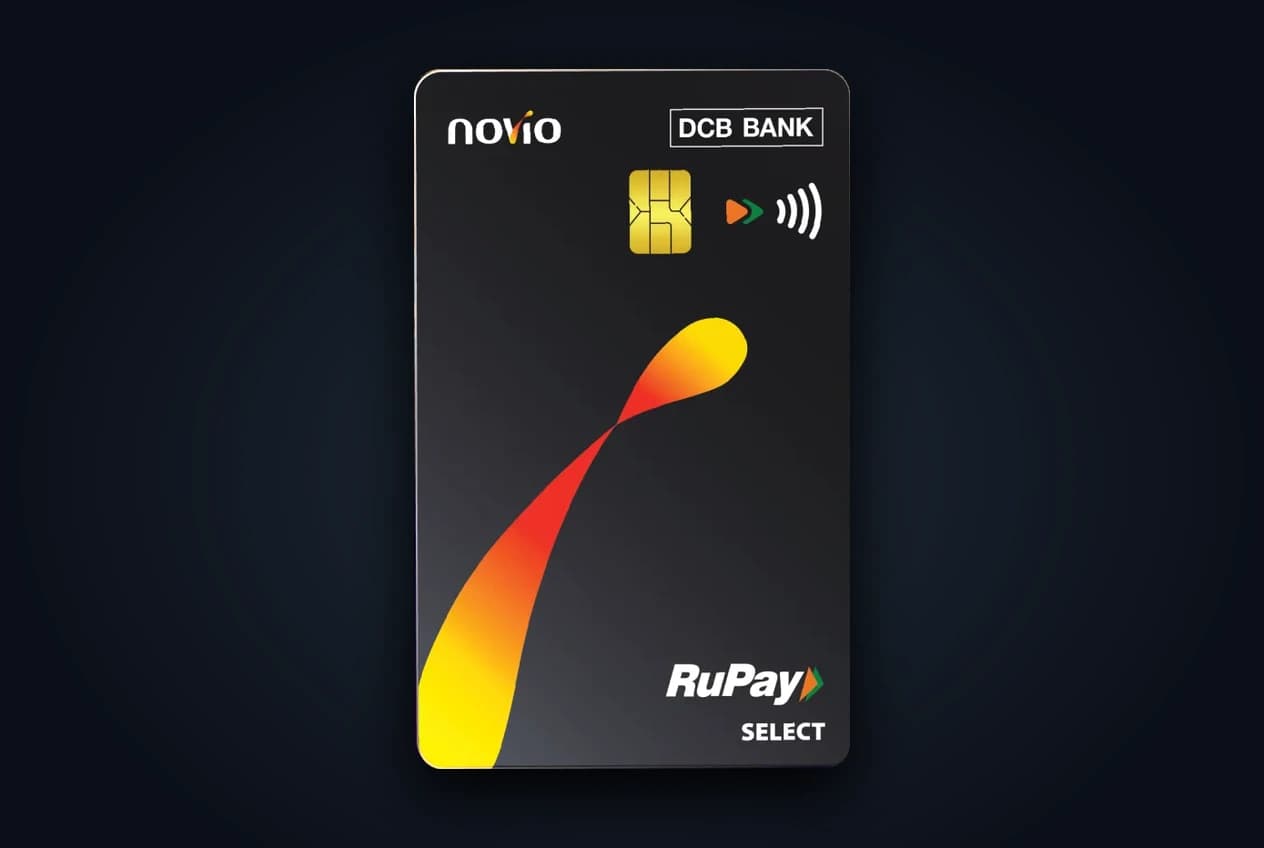
DCB novio Prime Credit Card
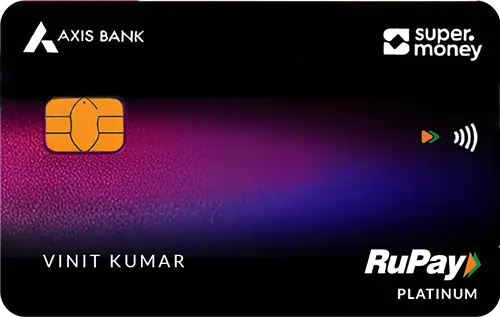
Axis Bank SuperMoney RuPay Credit Card
Frequently Asked Questions
What is the DCB novio Credit Card?
The DCB novio Credit Card is a secured RuPay credit card issued by DCB Bank in partnership with fintech platform novio. It is issued against a DCB Bank fixed deposit starting at ₹2,000, provides a credit line of 90% of the deposit, and supports UPI QR merchant transactions.
How does the advertised 10% UPI reward structure work?
When you make an eligible merchant P2M payment using the DCB novio RuPay card through the novio UPI app, you earn 5% novio Coins from the card plus another 5% from novio UPI, totalling 10% Coins. However, transactions through third-party apps like Google Pay or PhonePe only receive the card component.
What is one novio Coin actually worth in rupees?
novio Coins have no inherent monetary value and cannot ordinarily be converted to cash. They must be redeemed for brand vouchers, discounts, or app services where co-pay is often required. Therefore, 10 Coins per ₹100 spend is NOT equivalent to ₹10 cashback.
What is the difference between DCB novio Go and Prime?
DCB novio Go is a RuPay Platinum card requiring a minimum FD of ₹2,000 with zero lounge access. DCB novio Prime is a RuPay Select card requiring an FD of ₹25,000 and unlocks 1 complimentary domestic airport lounge visit per quarter (4 per calendar year).
Is the DCB novio Credit Card lifetime free?
Yes. Under DCB Bank's April 2026 KFS, both Go and Prime have ₹0 joining fee and ₹0 annual fee. However, closing the card within the first year of issuance incurs a ₹599 cancellation fee.
How much credit limit do I get on DCB novio?
DCB Bank provides a credit limit of exactly 90% of the linked fixed deposit. For example, a ₹2,000 FD gives a ₹1,800 limit, a ₹10,000 FD gives ₹9,000, and a ₹25,000 FD on Prime gives ₹22,500.
Does DCB novio require income proof or existing CIBIL history?
No. Because the card is secured by your own DCB fixed deposit, novio and DCB Bank do not require salary slips, ITR, or prior credit history, making it an accessible starter card for new-to-credit individuals.
Is there a daily cap on novio Coins earned on UPI?
Yes. UPI merchant rewards are strictly capped at 500 novio Coins per calendar day. At a 10% Coin rate, spending more than ₹5,000 in a single day yields no additional Coins on that day.
Are fuel purchases eligible for 10% novio Coins?
There is a conflict between marketing and bank terms. novio marketing mentions 10% Coins on fuel, but DCB Bank's official MITC explicitly excludes fuel from reward calculations. The card does provide a 1% fuel surcharge waiver (capped at ₹100 per cycle on spends up to ₹5,000).
Which transactions are excluded from earning novio Coins?
Excluded categories include utilities, government payments, insurance, educational institutions, gambling, wallet top-ups, rent, cash withdrawals, and UPI Lite transactions.
Can I use the DCB novio RuPay card on Google Pay or PhonePe?
Yes. You can link the RuPay credit card to third-party UPI apps for merchant QR payments. However, the additional 5% novio UPI bonus is exclusive to transactions initiated inside the novio app.
Does DCB novio offer airport lounge access?
The Go variant offers no lounge access. The Prime variant (RuPay Select, ₹25,000 FD) offers 1 complimentary domestic airport lounge visit per quarter (4 per year) with a ₹2 validation charge. It does not provide international lounge access.
What is the ₹23,000 annual savings claim?
The ₹23,000 headline combines maximum hypothetical monthly discounts across BookMyShow (₹3,000/yr), Amazon (₹12,000/yr), Zepto (₹1,800/yr), Swiggy (₹1,200/yr), plus a ₹5,000 voucher welcome package. It requires heavy, specific monthly merchant spends rather than guaranteed cashback.
How does DCB novio compare to flat cashback UPI cards like Kiwi or super.money?
Unsecured cards like PNB Kiwi offer 1.5% direct bank cashback, and Axis super.money offers up to 3% direct cashback. For users who qualify for unsecured credit, transparent bank cashback is financially superior to Coins without guaranteed cash value.
What happens to my fixed deposit while holding the card?
The deposit remains lien-marked by DCB Bank as collateral and continues earning interest (advertised up to 7% p.a.). If card dues remain unpaid up to 85 days past due, DCB Bank reserves the right to liquidate the deposit to recover outstanding amounts.
When do I get a physical plastic card?
For DCB novio Go, initial accounts receive a virtual card. A free physical card is dispatched once your cumulative linked fixed deposit reaches ₹10,000. For Prime, the physical card is included with the ₹25,000 FD.
Can I make P2P money transfers to friends using DCB novio UPI?
No. NPCI regulations prohibit person-to-person (P2P), person-to-person merchant (P2PM), and ATM cash withdrawals via RuPay credit cards on UPI. The card can only be used for merchant (P2M) purchases.

Founder & Editor, CardRecommend
Founder & Editor of CardRecommend. Dedicated to researching credit card reward structures, fee waivers, airport lounge policies, and calculating real user value across Indian financial products.